What is Form IT-204?
Quick answer: Form IT-204 is the New York Partnership Return. Partnerships do not pay personal income tax, but they must file Form IT-204 regardless of the amount of income if they have at least one partner who is a New York State resident individual, estate or trust, or any income, gain, loss or deduction from New York sources. A calendar-year return is due March 15 (March 16, 2026 for tax year 2025), and a fiscal-year return by the 15th day of the 3rd month after year-end. The return reports each partner’s share on Form IT-204-IP (New York Partner’s Schedule K-1).
IT-204 follows the federal Form 1065 closely: you transfer the amounts you reported federally into the corresponding sections, then add New York modifications, the New York allocation schedule and partner credit information. The return must include the same information as federal Form 1065, including any amended or superseding returns.
New York’s elective pass-through entity tax (PTET) is not paid on this return. The election and payments are made online each year, but if you opted into PTET, the instructions tell you to enter the total PTET liability with code 653 (and NYC PTET with code B53) in the flow-through credit information.
Key Figures — Form IT-204 and Instructions for Form IT-204 (IT-204-I, 2025)
- Who must file: any partnership with a New York resident individual, estate or trust partner, or any New York-source income, gain, loss or deduction, regardless of the amount of income.
- Due date: calendar-year returns by March 15 (March 16 for tax year 2025); fiscal-year returns by the 15th day of the 3rd month after the end of the tax year.
- Extension: request an automatic extension by the due date through the Tax Department’s website.
- Related forms: IT-204-IP (partner’s K-1), IT-204-CP (corporate partner), IT-204.1 (the partnership’s New York modifications), IT-204-LL (filing fee), IT-2658 and CT-2658 (estimated tax for nonresident individual and corporate partners).
- Filing fee (IT-204-LL): required of LLCs and LLPs with New York-source gross income of at least $1 million in the preceding tax year, and of single-member LLCs disregarded for federal tax with New York-source income.
- PTET: if the partnership opted in, report the PTET liability with code 653 (code B53 for NYC PTET).
- Where to mail: State Processing Center, PO Box 15198, Albany NY 12212-5198.
Source: the New York State Department of Taxation and Finance, Instructions for Form IT-204 (IT-204-I, 2025). Last verified October 14, 2026.
Who Must File Form IT-204?
File Form IT-204 if the partnership has at least one partner that is a New York State resident individual, estate or trust, or has any income, gain, loss or deduction from New York State sources. This includes limited liability companies, limited liability partnerships and other entities taxed as partnerships.
Partners that are entities. A partnership with partners that are partnerships or LLCs treated as partnerships must give each of them both Forms IT-204-IP and IT-204-CP, and file only IT-204-IP with Form IT-204. A partnership that has only a New York corporation or partnership partner is not required to file solely for that reason.
Portfolio investment partnerships mark the box in Item A: a limited partnership that meets the gross income requirement of IRC section 851(b)(2).
Estimated tax for nonresident partners. A partnership with New York-source income must make estimated tax payments for nonresident individual partners and corporate partners using Forms IT-2658 and CT-2658.
Common trap: thinking the PTET election is made on Form IT-204. The election and payments are made online each year; the IT-204 only records the PTET liability in the partner credit information.
How to File Form IT-204
- Gather your federal Form 1065 and Schedules K-1, including any amended or superseding versions.
- Transfer federal amounts into Sections 2 (ordinary business income), 3 (cost of goods sold), 4 (balance sheets), 6 (capital accounts) and 7 (partners’ share of income and deductions).
- Complete the New York sections: New York modifications (Section 8), other information (Section 9), the New York allocation schedule (Section 10) and partners’ credit information (Section 11).
- Prepare a Form IT-204-IP for each partner, and the other schedules and forms that apply.
- Pay any filing fee on Form IT-204-LL.
- E-file if you are subject to the e-file mandate, or mail the return.
When Is Form IT-204 Due?
Calendar-year partnerships must file on or before March 15 (the 2025 return was due March 16, 2026). Fiscal-year partnerships file by the 15th day of the third month after the end of the tax year, and a partnership that terminates and liquidates during its tax year files by the 15th day of the third month after the end of that accounting period. You may request an automatic extension of time to file by the due date, through the Tax Department’s website. Partnerships that keep their books outside the United States and Puerto Rico and qualify for a two-month federal extension have special codes for the extra time.
Where to Mail Form IT-204
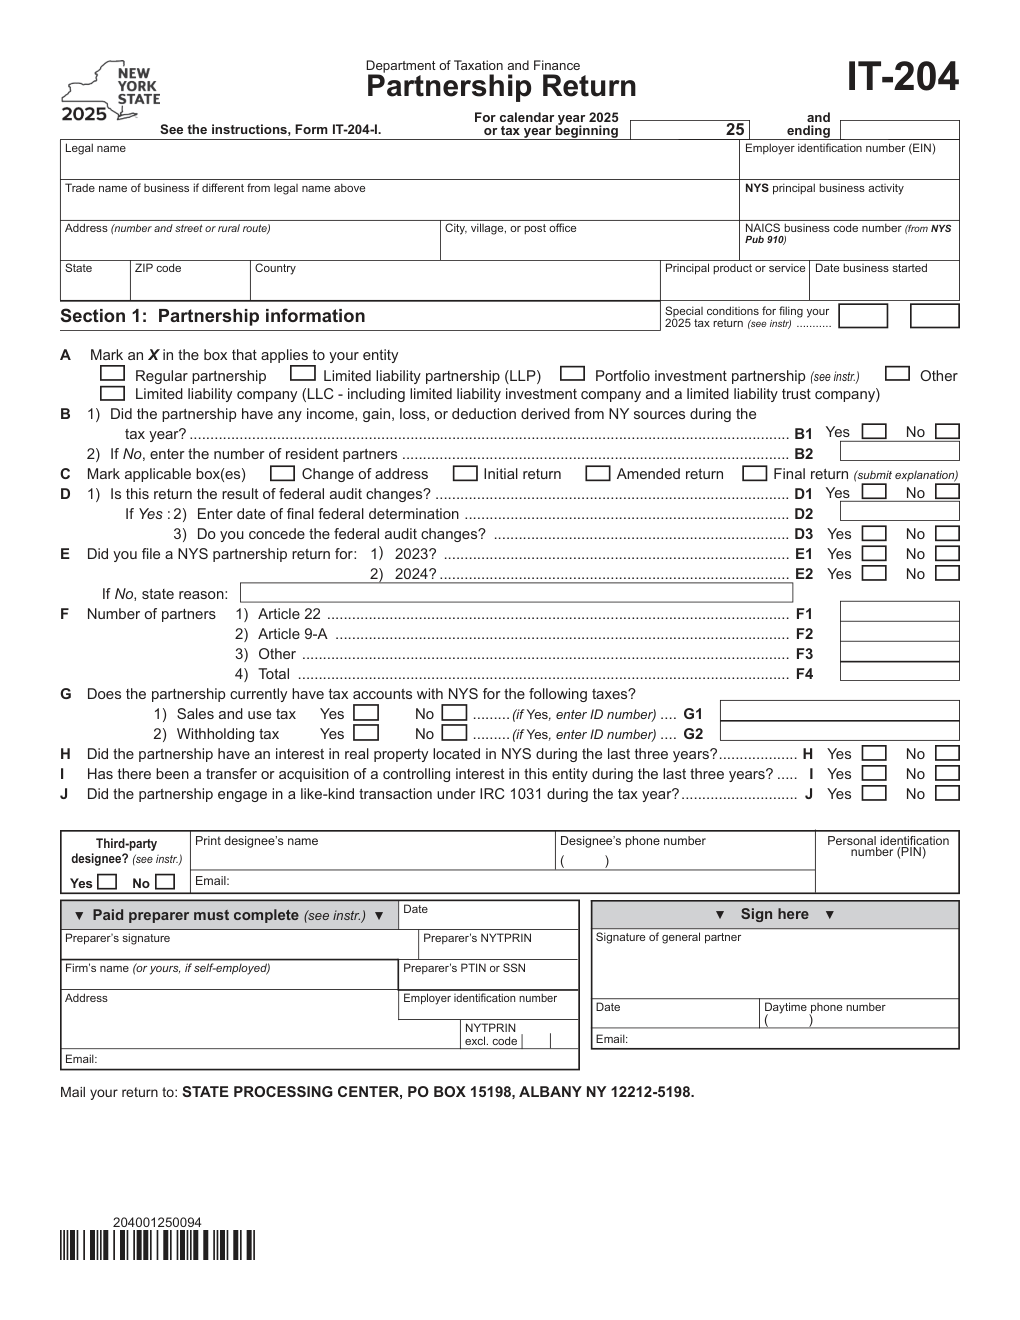
Mail your return to: State Processing Center, PO Box 15198, Albany NY 12212-5198. Private delivery services: see Publication 55. Use black ink only and do not use dollar signs, commas or decimal points on the form.
How to Complete Form IT-204 Line by Line
Section 1 — Partnership Information
Enter the partnership’s name, address, EIN and other identifying information, and mark whether it is a portfolio investment partnership (Item A). The section also covers the type of return and any extension or special codes.
Sections 2–4 — Ordinary Income, Cost of Goods Sold and Balance Sheets
Section 2 asks for federal ordinary business income (loss): transfer the amounts from the corresponding lines of federal Form 1065. Section 3 transfers cost of goods sold, and Section 4 transfers the balance sheets per books. Section 5, reconciliation of income per books with income per return, is not completed on Form IT-204.
Sections 6–7 — Capital Accounts and Partners’ Share of Income
Section 6 transfers the analysis of partners’ capital accounts. Section 7 transfers each partner’s share of income, deductions and other items from federal Schedule K, including the investment income and expense lines (federal Schedule K, lines 20a through 20c).
Sections 8–9 — New York Modifications and Other Information
Section 8 reports New York modifications (such as lines 108 and 110), using the worksheets in the instructions to determine the amounts. Section 9 collects other information, including a worksheet for line 116a that calculates amounts for partners who are not individuals.
Sections 10–11 — New York Allocation Schedule and Partners’ Credit Information
Section 10 is completed if the partnership carries on business inside and outside New York: it computes the percentage allocated to New York. Section 11 reports credit information passed through to partners, including investment, training and real property tax credit components, and the PTET liability (code 653) or NYC PTET liability (code B53) if the partnership opted to pay them. Part 2 of Section 11 covers flow-through credits, addbacks and recaptures, including those for Article 9-A corporate partners.
Common Mistakes to Avoid
- Skipping the return because the partnership had no income. The filing requirement applies regardless of the amount of income.
- Not giving corporate or partnership partners the right schedules. Partners that are partnerships need both Forms IT-204-IP and IT-204-CP.
- Forgetting IT-204-LL. LLCs and LLPs above the $1 million threshold owe a filing fee.
- Missing the March 15 date. Request the automatic extension by the due date.
- Entering PTET incorrectly. Use code 653 for PTET and B53 for NYC PTET.
- Using dollar signs or commas. The instructions say to omit them and to use black ink only.
Frequently Asked Questions
Who must file Form IT-204? Partnerships with a New York resident individual, estate or trust partner, or any New York-source income, gain, loss or deduction.
When is Form IT-204 due? March 15 for calendar-year partnerships (March 16 for tax year 2025); the 15th day of the 3rd month after year-end for fiscal years.
Is there a filing fee? Yes, Form IT-204-LL for LLCs and LLPs with New York-source gross income of at least $1 million in the preceding year, and for certain disregarded LLCs.
Is PTET paid on IT-204? No. The election and payments are made online; IT-204 reports the PTET liability with code 653.
Where do I mail Form IT-204? State Processing Center, PO Box 15198, Albany NY 12212-5198.
Do I need to match the federal return? Yes. IT-204 must include the same information reported on federal Form 1065, including amended or superseding returns.
Final Review Before Filing
- Federal Form 1065 and K-1s are complete and consistent.
- Sections 2, 3, 4, 6 and 7 match the federal amounts.
- New York modifications and the allocation schedule are completed.
- A Form IT-204-IP is prepared for each partner, with IT-204-CP for entity partners.
- IT-204-LL fee is paid if required.
- PTET liability is entered with code 653 if the entity opted in.
- The return is filed by March 15 or an extension is requested.
Sources & verification
- Issuing agency: New York State Department of Taxation and Finance
- Official documents: Form IT-204 (PDF) · IT-204-I instructions (PDF)
- Checked against: Form IT-204 and Instructions for Form IT-204 (IT-204-I, 2025)
- Last verified: October 14, 2026
Spot an error or an out-of-date figure? Tell us and we will check it against the official source.
General information from the official form and its instructions, not advice for your circumstances. See the full disclaimer.
More New York Tax Forms forms
- New York Form CT-3 — General Business Corporation Franchise Tax Return 2025-2026
- New York Form IT-201 — Resident Income Tax Return 2025-2026
- New York Form IT-201-X — Amended Resident Income Tax Return 2025-2026
- New York Form IT-203 — Nonresident and Part-Year Resident Income Tax Return 2025-2026
- New York Form IT-2104 — Employee’s Withholding Allowance Certificate
- New York Form IT-2105 — Estimated Tax Payment Voucher for Individuals
- New York Form IT-214 — Claim for Real Property Tax Credit for Homeowners and Renters
- New York Form IT-370 — Application for Automatic Six-Month Extension of Time to File for Individuals
- New York Form NYS-45 — Quarterly Combined Withholding, Wage Reporting, and Unemployment Insurance Return
- New York Form ST-100 — New York State and Local Quarterly Sales and Use Tax Return