

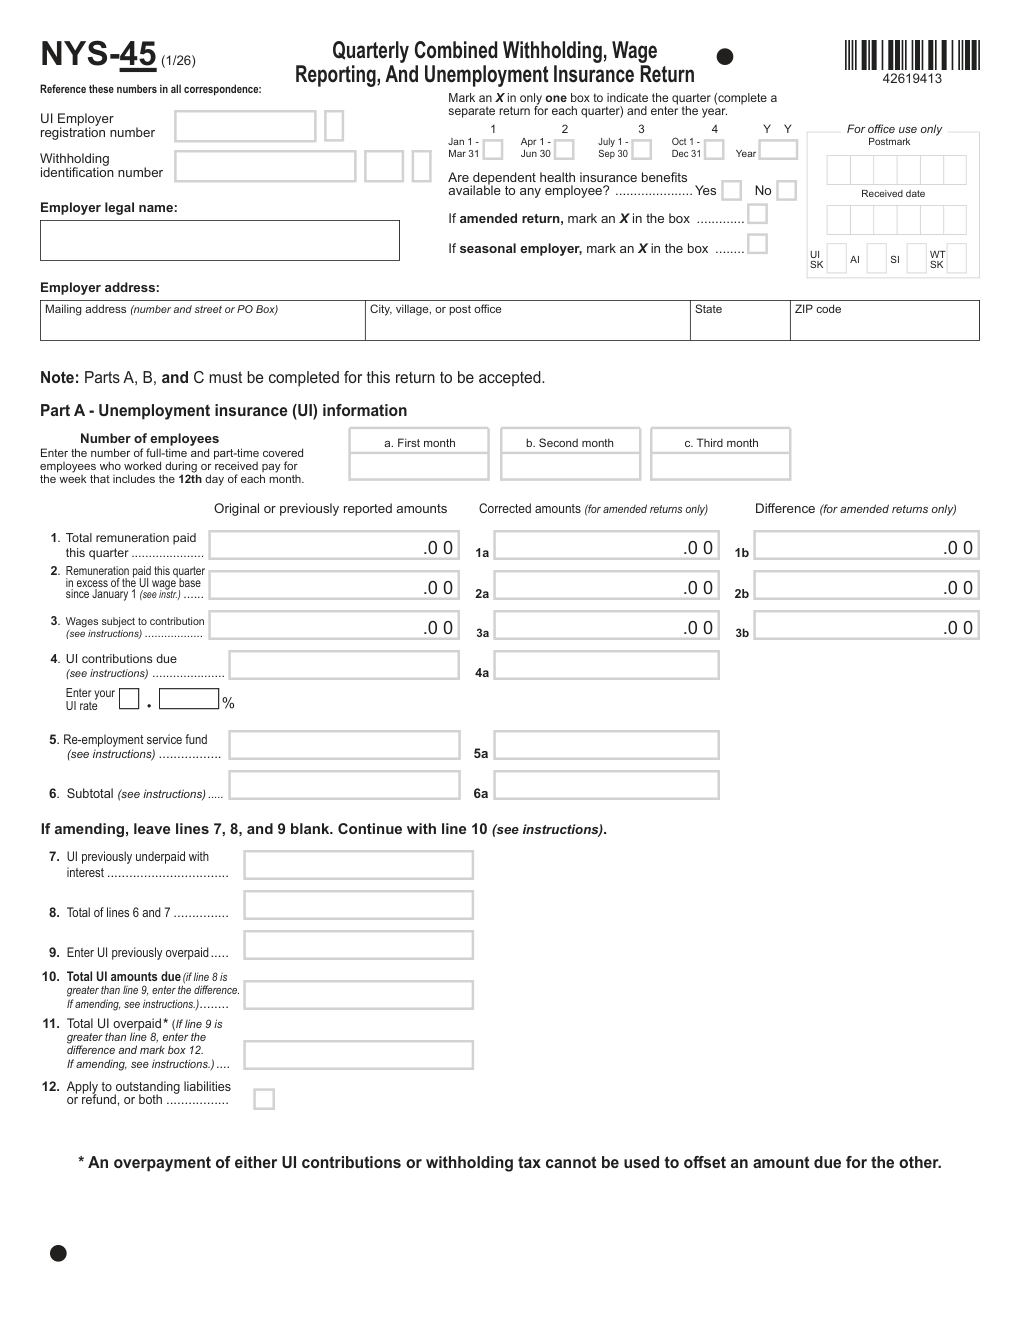
What is Form NYS-45?
Quick answer: Form NYS-45 is the quarterly payroll return New York employers use to report three things at once: unemployment insurance (UI) contributions, income tax withholding, and each employee’s wages. It is due the last day of the month after each quarter ends: April 30, July 31, October 31 and January 31. Employers subject to both UI and withholding complete Parts A, B and C every quarter. The return must be filed electronically, and paper filing may lead to penalties.
Federal payroll returns are split across several forms. New York combines them: one return carries the state’s UI contribution calculation (Part A), the reconciliation of withholding tax you have paid during the quarter (Part B), and a wage-and-withholding record for every employee (Part C). Because the state matches those wages to its own systems, mistakes on NYS-45 ripple into employees’ records and your UI experience rating.
The return is generally filed by the payroll or accounting person, but the employer signs it and is responsible for its accuracy. This guide follows the January 2026 (1/26) version of the form and instructions.
Key Figures — Form NYS-45 (1/26)
- Due dates: April 30 (Q1), July 31 (Q2), October 31 (Q3) and January 31 (Q4); if the date falls on a weekend or legal holiday, the next business day.
- UI wage base for 2026: $17,600. From 2026 it adjusts each January 1 to 18% of the state average annual wage, rounded up to the nearest $100.
- Default UI rate if none is on record: 9.825% plus 0.075% for the re-employment service fund, a total of 9.9%.
- Re-employment service fund: 0.075% of wages subject to contribution.
- UI contributions received more than 60 days after the due date cannot be credited for experience rating purposes.
- Filing method: electronic filing and payment are required; paper filers may be penalized.
Source: the New York State Department of Taxation and Finance and Department of Labor, Form NYS-45 (1/26) and Form NYS-45-I (1/26). Last verified September 29, 2026.
Who Must File Form NYS-45?
Employers subject to both UI contributions and withholding tax file Form NYS-45 every quarter, completing Parts A, B and C (boxes a through j). Other cases:
- UI only: complete Part A and Part C (boxes a to f), and enter zeros in withholding fields that do not apply.
- Withholding only: complete Part B and Part C (boxes a to e and g to j), with zeros in UI fields.
- Payers of gambling winnings (other than NYS Lottery) report them as wages and complete Part B and the Part C boxes for winnings withheld.
- Seasonal employers with at least one quarter without wages subject to UI and withholding may mark the seasonal box after filing one return, and must mark it on every return they file that year.
- Nonprofit, governmental and tribal employers who elected to reimburse UI benefits complete the employee count, Part A line 1, Parts B and C and the signature, and leave other Part A lines blank.
Parts A, B and C must all be completed for the return to be accepted. An employer with no payroll completes Parts A and B and enters 0 in Part C, line 24.
Common trap: employers with no payroll skip the return. The instructions require Parts A and B and a 0 on Part C, line 24 for a quarter with no wages.
How to File Form NYS-45
- File electronically. The Tax Department offers three methods: Web File, Web Upload and Federal/State Employment Taxes (FSET) compatible software. Web File accepts wage data for up to 1,000 employees by manual entry or .csv upload, and more by flat file upload.
- Pay electronically the balance due; Web File also lets you submit payment by ACH debit.
- Complete a separate return for each quarter and mark the quarter and two-digit year.
- Use original forms if you file on paper, not photocopies, with black ink and no punctuation except decimal points.
- Sign the return. It must be signed by an individual owner, an officer of a corporation, an authorized partner or member, or an authorized government official; a payroll service or paid preparer completes the bottom section.
When Is Form NYS-45 Due?
| Quarter | Due date |
|---|---|
| January 1 – March 31 | April 30 |
| April 1 – June 30 | July 31 |
| July 1 – September 30 | October 31 |
| October 1 – December 31 | January 31 |
When the date is a Saturday, Sunday or legal holiday, you may file on the next business day. Late returns and payments bear interest and penalties, and the penalty can grow the later the return is filed. UI contributions received more than 60 days after the due date cannot be credited to your account for experience rating, which can affect future UI rates and the credit you may claim on federal Form 940.
Where to Mail Form NYS-45
Employers must file and pay electronically. If you file on paper despite the mandate, mail it to NYS Employment Contributions and Taxes, PO Box 4119, Binghamton NY 13902-4119, and expect possible penalties. Make payment payable to NYS Employment Contributions and Taxes.
How to Complete Form NYS-45 Line by Line
Header — Quarter, Registration Numbers and Employer Information
Enter your seven-digit UI employer registration number and check digit, and your nine-digit federal EIN with the two-digit NYS suffix and check digit. Mark the one quarter you are reporting and the year, answer whether dependent health insurance was available to any employee, and mark the amended-return or seasonal-employer boxes if they apply. The address you enter replaces the mailing address on record for all withholding and UI notices.
Part A — Unemployment Insurance (Lines 1–12)
First enter the number of full-time and part-time covered employees who worked or were paid for the pay period that includes the 12th day of each month.
| Line | What to enter |
|---|---|
| Line 1 | Total remuneration paid this quarter (including amounts over the UI wage base). |
| Line 2 | Remuneration above the wage base since January 1 for employees who have passed it. |
| Line 3 | Line 1 minus line 2, the wages subject to contribution. |
| Line 4 | Multiplies line 3 by your UI rate. |
| Line 5 | The re-employment service fund at 0.075% of line 3. |
| Line 6 | Total of the lines above. |
Lines 7 to 12 handle underpaid or overpaid UI from earlier periods, and give the total due or overpaid.
Part B — Withholding Tax (Lines 13–22)
Line 13 is total tax withheld, taken from Part C, line 24. Line 14 is any withholding credit from the previous quarter, line 15 is the payments you made with Form NYS-1 for the quarter, and line 17 totals payments (lines 14 to 16, with 16 and 18 for amended returns only). Line 20 is the withholding amount due if line 13 is more than line 19, and line 21 is an overpayment that can be refunded (21a) or credited to the next quarter (21b). Line 22 adds lines 10 and 20 into one remittance payable to NYS Employment Contributions and Taxes. An overpayment of UI or withholding tax cannot offset an amount due for the other.
Part C — Employee Wage and Withholding Reporting (Boxes a–j)
Report every employee paid during the quarter. Box a is the Social Security number, boxes b, c and d are last name, first name and middle initial, box e is the wage type, box f is total UI remuneration, box g is gross federal wages or distribution before any allocation, and boxes h, i and j are New York State, New York City and Yonkers tax withheld. Do not use negative numbers in boxes f through j. Report dollars and cents or whole dollars, but be consistent for every employee. Enter page totals for each page, then
| Line | What to enter |
|---|---|
| Line 23 | Total of the lines above. |
| Line 24 | Adds boxes h, i and j and carries to Part B, line 13. |
Signature and Paid Preparer Section
Sign, print your name and title, and add the date and telephone number. The signature certifies that the return is true and correct and that the remuneration reported is all remuneration paid in the quarter for covered employment. Payroll services and paid preparers must complete the section at the bottom, including their New York tax preparer registration number (NYTPRIN) or an exclusion code.
Common Mistakes to Avoid
- Filing on paper. Electronic filing and payment are required, and paper returns may be penalized.
- Skipping a quarter with no payroll. File Parts A and B and enter 0 in Part C, line 24.
- Leaving Part C incomplete. All three parts are needed for acceptance, and the totals must match Part B line 13.
- Entering negative amounts. Credits and minus signs are not allowed in boxes f to j.
- Using the wrong UI rate. An entered rate below your assigned rate leaves an underpayment billed with 12% annual interest.
- Correcting only the changed employee. Amended returns must be complete, with Parts A, B and every wage record.
- Paying UI more than 60 days late. The payment will not count for experience rating.
Frequently Asked Questions
Who files Form NYS-45? New York employers subject to UI contributions, withholding tax or both file it every quarter.
Can I file NYS-45 on paper? Employers must file electronically, and paper returns may be penalized.
What is the 2026 unemployment insurance wage base? $17,600.
How do I amend a NYS-45? Complete a new NYS-45, mark the Amended return box, enter the quarter and year and complete the form in its entirety.
Do I report federal audit changes on NYS-45? Yes, within 90 days of the final federal determination, with a copy of the determination attached.
What if I have no employees this quarter? Complete Parts A and B and enter 0 in Part C, line 24.
Final Review Before Filing
- The right quarter and year are marked and the return is for that quarter only.
- UI registration and withholding identification numbers are entered.
- Part A wages, excess wages and the UI rate are correct for 2026 (wage base $17,600).
- Part B line 13 equals Part C line 24.
- Every employee has a record in Part C, with no negative amounts.
- The return is signed and filed electronically by the due date, with payment.
- If amending, all parts are completed and the amended box is marked.
Sources & verification
- Issuing agency: New York State Department of Taxation and Finance and Department of Labor
- Official documents: Form NYS-45 (PDF) · Form NYS-45-I instructions (PDF)
- Checked against: Form NYS-45 (1/26) and Form NYS-45-I (1/26)
- Last verified: September 29, 2026
Spot an error or an out-of-date figure? Tell us and we will check it against the official source.
General information from the official form and its instructions, not advice for your circumstances. See the full disclaimer.
More New York Tax Forms forms
- New York Form IT-201 — Resident Income Tax Return 2025-2026
- New York Form IT-201-X — Amended Resident Income Tax Return 2025-2026
- New York Form IT-203 — Nonresident and Part-Year Resident Income Tax Return 2025-2026
- New York Form IT-2104 — Employee’s Withholding Allowance Certificate
- New York Form IT-2105 — Estimated Tax Payment Voucher for Individuals
- New York Form IT-214 — Claim for Real Property Tax Credit for Homeowners and Renters
- New York Form IT-370 — Application for Automatic Six-Month Extension of Time to File for Individuals
- New York Form ST-100 — New York State and Local Quarterly Sales and Use Tax Return