

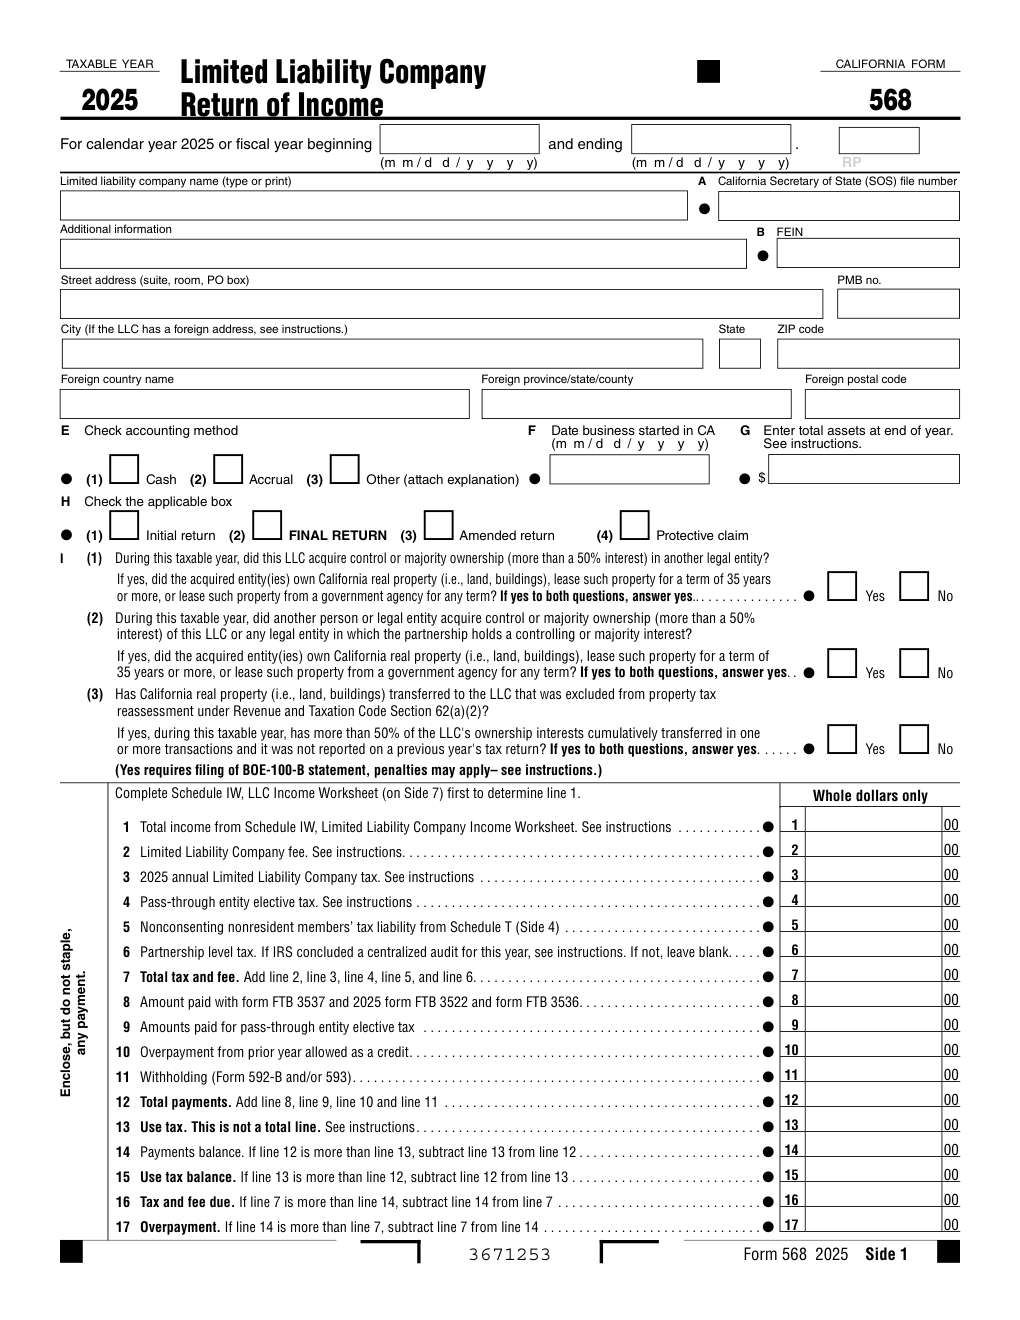
What is Form 568?
Quick answer: Form 568 is the California Limited Liability Company Return of Income. Every LLC that is doing business in California, organized in California, or registered with the California Secretary of State files it, unless the LLC is taxed as a corporation. It reports the $800 annual LLC tax and the LLC fee (owed once total California income reaches $250,000), and for a multiple-member LLC it reports the income that flows to the members. A calendar-year LLC taxed as a partnership files by the 15th day of the 3rd month (March 15), with an automatic 7-month extension. The $800 itself is not paid with the return: it goes in with FTB 3522.
Form 568 does three jobs at once. It figures the LLC fee from the LLC’s total California income, it reports the annual tax and any elective or nonconsenting-member taxes, and it carries the partnership-style schedules (B, K and K-1) that show each member’s share of income, deductions and credits.
A single-member LLC that is disregarded for federal tax still files Form 568 to pay the tax and fee, but it completes fewer schedules: the single owner reports the LLC’s income on the owner’s own return.
Key Figures — Form 568 (2025 booklet, REV 03-26)
- Annual LLC tax: $800, paid with FTB 3522, not with Form 568.
- LLC fee (total California income from Schedule IW): $900 for $250,000–$499,999; $2,500 for $500,000–$999,999; $6,000 for $1,000,000–$4,999,999; $11,790 for $5,000,000 and over. Below $250,000 there is no fee.
- Due date: 15th day of the 3rd month after year-end for LLCs classified as partnerships and for single-member LLCs owned by pass-through entities; 15th day of the 4th month after the owner’s year-end for other single-member LLCs.
- Automatic extension: 7 months for LLCs classified as partnerships; 6 months for disregarded single-member LLCs (7 if owned by a partnership). It does not extend the time to pay the LLC fee or nonconsenting nonresident members’ tax; use FTB 3537 for those.
- Estimated fee: due by the 15th day of the 6th month of the taxable year with FTB 3536; underpaying it adds a 10% penalty on the shortfall unless the estimate equals the prior year’s fee.
- Late filing: $18 per member per month (up to 12 months) for failing to file or to show required information; and 5% of the unpaid tax per month, capped at 25%.
- Pass-through entity elective tax: 9.3% of qualified net income, reported on line 4 (see the FTB 3893 guide).
Source: the Franchise Tax Board, 2025 Limited Liability Company Tax Booklet (Form 568 and instructions). Last verified October 14, 2026.
Who Must File Form 568?
File Form 568 if the LLC is doing business in California, is organized in California, is organized elsewhere but registered with the California Secretary of State, or has California-source income (with exceptions for nonregistered foreign LLCs, which may file Form 565 instead).
Do not file Form 568 if the LLC elected to be taxed as a corporation for federal purposes. An LLC taxed as a corporation files Form 100 (or Form 100S as an S corporation). An LLC with a taxable year of 15 days or less that did no business in the state in that period also does not file.
A registered LLC files even if inactive. If the LLC is registered in California but is not doing business and has no California-source income, it satisfies the filing rule by completing Form 568 with all supplemental schedules, attaching Schedules K-1 (568) for members with California addresses, writing “SB 1106 Filing” at the top of Side 1 and entering the number of members in Question K.
Doing-business tests. For 2025 an LLC is doing business if it is organized or commercially domiciled in California, or its California sales exceed the lesser of $757,070 or 25% of total sales, its California property exceeds the lesser of $75,707 or 25% of total property, or its California payroll exceeds the lesser of $75,707 or 25% of total compensation.
Common trap: sending the $800 annual tax with Form 568. The instructions say not to: pay it with FTB 3522 so it is applied to the LLC’s account, and enter it on line 8.
How to File Form 568
- Decide how the LLC is classified. Partnership or disregarded entity files Form 568; an LLC taxed as a corporation files Form 100 or 100S.
- Complete Schedule IW (Side 7) first to get total California income for line 1, which sets the LLC fee on line 2.
- Complete the member schedules: Schedule B (income and deductions), Schedule K and a Schedule K-1 (568) for each member (single-member LLCs do not file K-1s). Attach the federal Form 8832 if one was filed.
- Get consent forms from nonresident members. Every nonresident member must sign FTB 3832; for a member who does not, the LLC pays tax on that member’s share at the highest marginal rate (Schedule T).
- E-file if required. California requires business entities that prepare an original or amended return with software to e-file. Pay with Web Pay, a credit card or electronic funds withdrawal, or mail FTB 3588 with a check.
- Amend with a new Form 568 and an amended K-1 for each affected member; attach a statement explaining each change. After a federal change, file within six months of the final federal determination if the fee or a member’s tax is affected.
When Is Form 568 Due?
For an LLC classified as a partnership the return is due the 15th day of the 3rd month after the close of the taxable year, which is March 15 for a calendar-year LLC. A single-member LLC owned by an S corporation, partnership or partnership-classified LLC follows the same date. Any other single-member LLC files by the 15th day of the 4th month after the close of its owner’s taxable year. When the date falls on a weekend or holiday, the deadline moves to the next business day. California does not require a written extension request: an LLC in good standing gets 7 months automatically (6 for a disregarded single-member LLC owned by someone other than a partnership), unless it is suspended or forfeited. The extension does not extend payment of the LLC fee or the nonconsenting nonresident members’ tax; send those with FTB 3537 by the original due date.
Where to Mail Form 568
Return with payment: Franchise Tax Board, PO Box 942857, Sacramento CA 94257-0501. Return without payment, a refund return, or a return paid electronically: PO Box 942857, Sacramento CA 94257-0500. E-filed return with a check (FTB 3588): PO Box 942857, Sacramento CA 94257-0531. Make the check payable to the Franchise Tax Board and write the SOS file number, FEIN and the form name and year on it. Private delivery services cannot deliver to PO boxes; use FRANCHISE TAX BOARD, SACRAMENTO CA 95827 instead.

How to Complete Form 568 Line by Line
Top of the Return — Name, SOS File Number, FEIN and Items E–H
Enter the LLC’s name as it appears with the Secretary of State, the SOS file number and the FEIN. Item E is the accounting method (cash, accrual or other with an attached explanation),
| Line | What to enter |
|---|---|
| F | The date business started in California. |
| G | Total assets at year-end. Item H marks an initial, final or amended return, or a protective claim. |
A short-period return, filed when an LLC is created or ends during the year, has “Short Period” written at the top of Side 1.
Question I — Change in Control and Real Property
Question I asks whether the LLC acquired a majority interest in another legal entity, whether another person acquired control of the LLC, and whether California real property excluded from property-tax reassessment has been transferred to the LLC. A “Yes” answer to the full question requires filing a BOE-100-B statement with the Board of Equalization, and penalties may apply.
Lines 1–3 — Total Income, LLC Fee and Annual Tax
| Line | What to enter |
|---|---|
| Line 1 | Total California income from Schedule IW, line 17, and cannot be negative. |
| Line 2 | The LLC fee: nothing under $250,000, then $900, $2,500, $6,000 or $11,790 for the brackets in the Key Figures. If the FTB finds that several LLCs were formed mainly to reduce fees, it can aggregate the income of commonly controlled LLCs (more than 50% of capital or profits). |
| Line 3 | The $800 annual tax for the year; a deployed-military LLC that qualifies enters zero on lines 2 and 3 and prints “Deployed Military” in the top margin. |
Lines 4–7 — Elective Tax, Nonconsenting Members’ Tax and Total
| Line | What to enter |
|---|---|
| Line 4 | The pass-through entity elective tax from FTB 3804, Part I, line 3. |
| Line 5 | The nonconsenting nonresident members’ tax from Schedule T. |
| Line 6 | Partnership-level tax that results from an IRS centralized partnership audit and is normally reported on an amended return; leave it blank otherwise. |
| Line 7 | Adds lines 2 through 6. |
Lines 8–12 — Payments and Credits
| Line | What to enter |
|---|---|
| Line 8 | What the LLC paid with FTB 3537, FTB 3522 and FTB 3536 (including the $800 annual tax). |
| Line 9 | Elective-tax payments, including those made with FTB 3893 or electronically, which cannot be combined with other tax payments. |
| Line 10 | An overpayment credited from the prior year. |
| Line 11 | Withholding from Form 592-B or 593; attach the form to the front of the return. |
| Line 12 | Totals lines 8 through 11. |
Lines 13–17 — Use Tax, Payments Balance and Amount Due
| Line | What to enter |
|---|---|
| Line 13 | Use tax on out-of-state purchases where no California sales or use tax was paid. An LLC that has, or must hold, a seller’s permit, or that has more than $10,000 of such purchases per calendar year (excluding vehicles, vessels and aircraft), reports use tax to the California Department of Tax and Fee Administration instead. |
| Lines 14 and 15 | Show the payments or use-tax balance. |
| Line 16 | Tax and fee due. |
| Line 17 | An overpayment. |
| Line 20 | Penalties and interest. |
| Line 21 | The total amount due. |
Schedule IW, Schedule B, Schedule K and Schedule K-1 (568)
Schedule IW builds the total income that sets the fee. Schedule B and Schedule K follow federal Form 1065 reporting, with California-specific differences such as separate gain and loss lines (10a/10b and 11b/11c). Schedule K-1 (568) gives each member a share of income, deductions and credits; the number of K-1s must equal the members entered on Question K. A disregarded single-member LLC completes Schedule B and K only if its Schedule B income or loss, or Schedule K total, reaches $3,000,000, but it always completes Schedule IW.
Common Mistakes to Avoid
- Mailing the $800 with the return. It belongs with FTB 3522.
- Skipping Schedule IW. Line 1 and the fee depend on it, and a disregarded LLC still completes it.
- Forgetting FTB 3832 for nonresident members. Without it the LLC owes tax on that member’s share at the highest marginal rate.
- Assuming the extension covers the fee. The fee and nonconsenting-member tax are due by the original due date; use FTB 3537.
- Missing the estimated fee. A 10% penalty applies when the FTB 3536 estimate is below the fee owed, unless it equals last year’s fee.
- Filing the wrong return for an LLC taxed as a corporation. That LLC files Form 100 or 100S.
- Treating an inactive registered LLC as exempt. It still files, using the SB 1106 filing procedure.
Frequently Asked Questions
Who files Form 568? Every LLC doing business in California, organized in California or registered with the California Secretary of State, unless it is taxed as a corporation.
When is Form 568 due? The 15th day of the 3rd month after year-end for LLCs classified as partnerships (March 15 for calendar-year LLCs); the 15th day of the 4th month after the owner’s year-end for most other single-member LLCs.
How much is the LLC fee? $900, $2,500, $6,000 or $11,790 depending on total California income, and no fee below $250,000.
Is the LLC fee the same as the $800 annual tax? No. The $800 is a flat annual tax paid with FTB 3522; the fee is based on income and is reported on Form 568.
Does a single-member LLC file Form 568? Yes. It files Side 1 through 3, Schedule IW and pays the tax and fee, and completes Schedules B and K only above the $3,000,000 thresholds.
Do I need an extension request? No. California grants 7 months automatically to partnership-classified LLCs in good standing; payments are still due by the original date.
Final Review Before Filing
- The LLC is classified correctly (partnership or disregarded: Form 568).
- Schedule IW is complete and line 1 matches line 17 of Schedule IW.
- The LLC fee on line 2 matches the bracket for line 1.
- The $800 annual tax was paid with FTB 3522 and appears on line 8.
- An FTB 3832 is on file for every nonresident member.
- The number of Schedules K-1 (568) equals Question K.
- Estimated fee and extension payments are included on line 8.
- The return is e-filed if it was prepared with software, or mailed to the correct PO box.
Sources & verification
- Issuing agency: California Franchise Tax Board
- Official documents: Form 568 (PDF) · 2025 LLC Tax Booklet (PDF)
- Checked against: Form 568 (2025) and the 2025 Limited Liability Company Tax Booklet (REV 03-26)
- Last verified: October 14, 2026
Spot an error or an out-of-date figure? Tell us and we will check it against the official source.
General information from the official form and its instructions, not advice for your circumstances. See the full disclaimer.
More California Tax Forms forms
- California Form 100 — Corporation Franchise or Income Tax Return 2025-2026
- California Form 540 — Resident Income Tax Return 2025-2026
- California Form 540-ES — Estimated Tax for Individuals
- California Form 540NR — Nonresident or Part-Year Resident Income Tax Return 2025-2026
- California Form DE 4 — Employee’s Withholding Allowance Certificate
- California FTB 3514 — California Earned Income Tax Credit
- California FTB 3522 — LLC Tax Voucher
- California FTB 3893 — Pass-Through Entity Elective Tax Payment Voucher
- California Schedule CA (540) — California Adjustments, Residents