
What is FTB 3893?
Quick answer: FTB 3893 is the voucher a California pass-through entity (PTE) uses to pay the elective tax: a partnership, LLC taxed as a partnership or S corporation can elect to pay 9.3% of its qualified net income at the entity level, and its owners get a matching personal income tax credit. For taxable years beginning in 2026 through 2030 the entity makes two payments: the first by June 15 of the election year (at least $1,000 or 50% of the prior year’s elective tax, whichever is greater) and the rest by the original due date of the return. Missing or shorting the June 15 payment no longer blocks the election, but the owners’ credit is reduced by 12.5% of the unpaid amount. If you pay online, do not mail the voucher.
California’s elective tax is a way for a pass-through entity to pay tax that its owners would otherwise pay personally, with the entity-level payment generating a credit for the owners. The election is made on an original, timely filed return and is irrevocable for that taxable year.
The election itself is made on the entity’s return (Form 100S, 565 or 568), supported by FTB 3804, which calculates the tax. FTB 3893 is only the payment voucher.
Key Figures — FTB 3893 (2026 instructions)
- Rate: 9.3% of qualified net income (QNI), the sum of each consenting qualified taxpayer’s pro rata or distributive share and guaranteed payments subject to California personal income tax.
- Years covered: taxable years beginning on or after January 1, 2026 and before January 1, 2031. The earlier version of the program ended with taxable years beginning before January 1, 2026.
- Payment 1: on or before June 15 of the election year; at least $1,000 or 50% of the prior year’s elective tax, whichever is greater.
- Payment 2: the remaining tax by the original due date of the return, without extensions: March 15, 2027 for a calendar-year 2026 election, or the 15th day of the 3rd month after a fiscal year-end.
- Short or missed June 15 payment: the election is still valid for 2026 and later years, but the credit allowed to each qualified taxpayer is reduced by 12.5% of the taxpayer’s pro rata share of the unpaid amount due.
- How to pay: electronic funds withdrawal, Web Pay for Businesses, or the voucher. Elective tax cannot be combined with other tax payments.
Source: the Franchise Tax Board, 2026 Instructions for Form FTB 3893. Last verified October 14, 2026.
Who Must File FTB 3893?
Eligible entities are qualified pass-through entities: an entity taxed as a partnership or an S corporation. The credit goes to the entity’s owners who are qualified taxpayers; an owner that is itself a partnership cannot claim it.
Disregarded entities and their owners generally cannot receive the credit, except a disregarded single-member LLC owned by an individual, fiduciary, estate or trust subject to California personal income tax.
Owners do not all have to consent. A partner, shareholder or member who does not consent does not prevent the entity from making the election.
S corporations that are required to pay electronically must also remit the elective tax electronically, which they can do by EFW or Web Pay.
Common trap: using FTB 3893 for estimated tax or an extension payment. The instructions say not to use it for business entity estimated tax or automatic extension payments.
How to File FTB 3893
- Calculate the tax on FTB 3804 and make the election on a timely filed original return (the elective tax is reported on Form 568, line 4, or the equivalent line of Form 565 or 100S).
- Prefer electronic payment. Use Web Pay for Businesses at ftb.ca.gov/pay (immediate or scheduled up to a year ahead) or EFW in your software; if so, do not file FTB 3893.
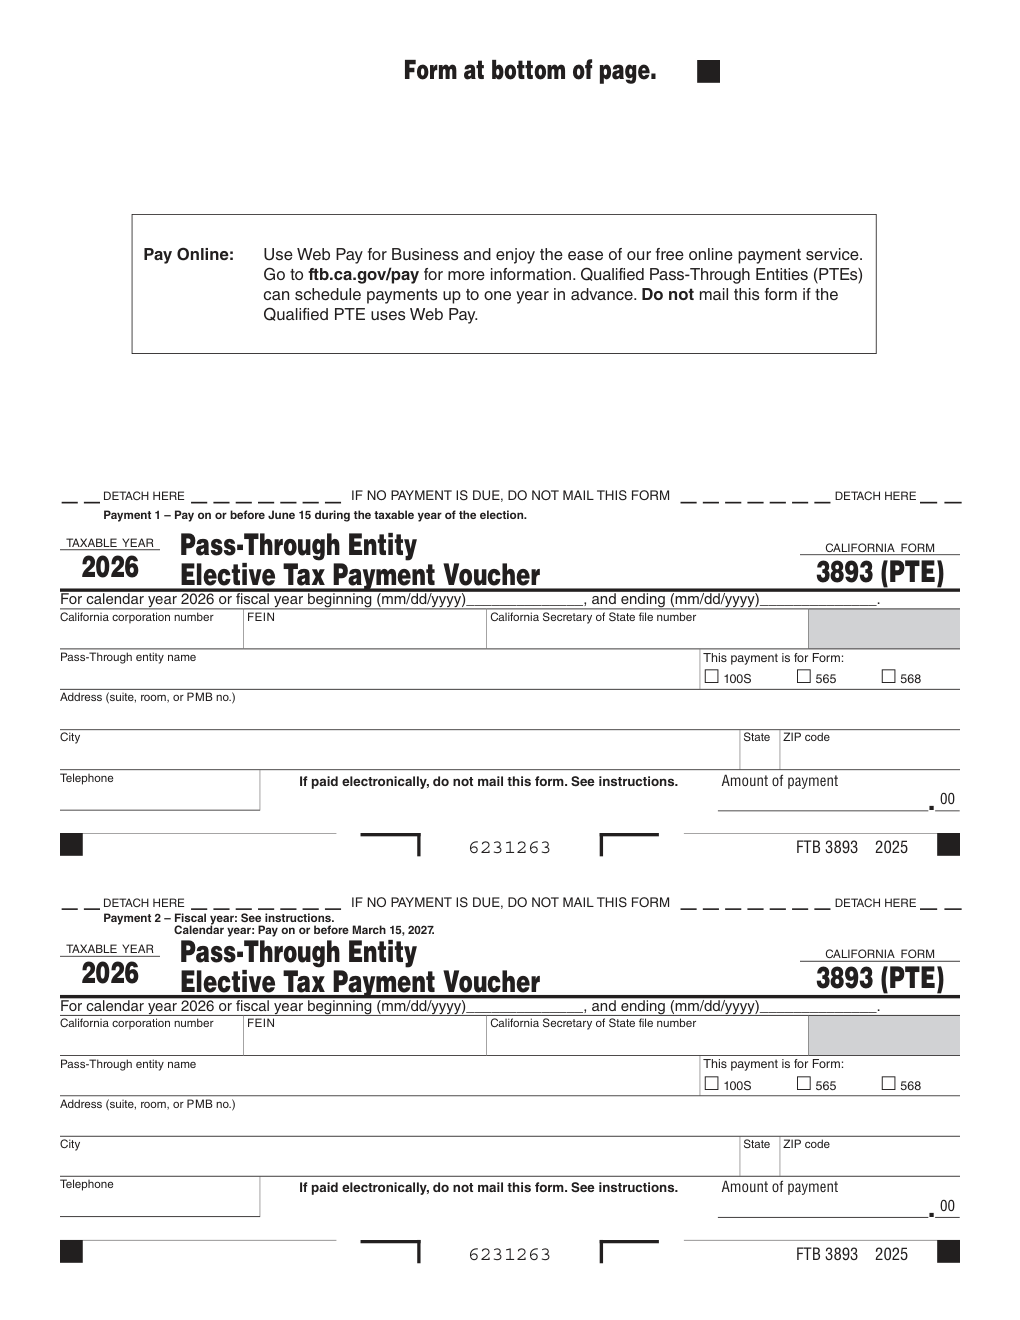
- If paying by check or money order, complete the voucher in black or blue ink and make the check payable to the “Franchise Tax Board.” Write the California corporation number, SOS file number or FEIN, the taxable year and “FTB 3893” on it.
- Check one box showing whether the payment is for Form 100S, 565 or 568.
- Enclose, but do not staple, the check with the voucher, and mail it to the address below.
When Is FTB 3893 Due?
Payment 1 is due on or before June 15 of the taxable year of the election. The minimum is $1,000 or 50% of the elective tax paid for the prior taxable year, whichever is greater; in the first year of the election the $1,000 minimum applies. Payment 2 is the remaining elective tax, due on or before the due date of the original return for the election year, without regard to extensions: March 15, 2027 for a calendar-year entity electing for 2026, or the 15th day of the 3rd month after the close of a fiscal year. When a due date falls on a weekend or holiday, it moves to the next business day. Because the June 15, 2026 date has already passed, a calendar-year entity that missed it can still elect for 2026 and pay the rest by March 15, 2027, accepting the 12.5% credit reduction.
Where to Mail FTB 3893
Mail the voucher and your unstapled check or money order to: Franchise Tax Board, PO Box 942857, Sacramento CA 94257-0531. Do not mail the voucher if you paid electronically or no payment is due.

How to Complete FTB 3893 Line by Line
Top of the Voucher — Taxable Year and Which Return the Payment Is For
Each voucher is for a calendar year or a fiscal year beginning and ending on the dates you enter. Check only one box: Form 100S (S corporation), Form 565 (partnership) or Form 568 (LLC). The form has separate vouchers for Payment 1 and Payment 2, so use the right one for the payment you are making.
California Corporation Number, FEIN and SOS File Number
Enter the California corporation number, the federal employer identification number (FEIN) and the California Secretary of State file number as they apply to the entity, plus the entity name, address (use PMB first for a private mailbox) and a telephone number. These identifiers are how the FTB applies the payment to the right account.
Amount of Payment
Payment 1 is at least $1,000 or 50% of the elective tax paid for the prior taxable year, whichever is greater. Payment 2 is the remaining elective tax. The total elective tax is 9.3% of the entity’s qualified net income, so calculate it on FTB 3804 first. The amount on each voucher is entered with cents.
Common Mistakes to Avoid
- Paying twice. If you pay by EFW or Web Pay, do not also file the voucher.
- Combining the elective tax with other payments. It must be paid separately from estimated tax and other business taxes.
- Using FTB 3893 for estimated tax or an extension. It is for the elective tax only.
- Checking more than one box for the return type.
- Assuming a missed June 15 payment ends the election for 2026 and later. It does not, but the credit shrinks by 12.5% of the unpaid share.
- Missing the second payment. The remainder is due by the original return due date, without extensions.
Frequently Asked Questions
What is the California PTE elective tax rate? 9.3% of the entity’s qualified net income.
When are the payments due? Payment 1 by June 15 of the election year; Payment 2 by the original due date of the return (March 15 for a calendar-year entity).
What happens if I miss the June 15 payment? For taxable years beginning in 2026 or later, you can still elect, but each qualified taxpayer’s credit is reduced by 12.5% of their share of the unpaid amount.
How much is the first payment? The greater of $1,000 or 50% of the elective tax paid for the prior year.
Does the election run through 2030? Yes. The extended program covers taxable years beginning on or after January 1, 2026 and before January 1, 2031.
Where do I mail the voucher? Franchise Tax Board, PO Box 942857, Sacramento CA 94257-0531, unless you pay electronically.
Final Review Before Filing
- The entity is an eligible partnership, LLC taxed as a partnership or S corporation.
- The elective tax was calculated on FTB 3804.
- Payment 1 reached the FTB by June 15, or you understand the 12.5% credit reduction.
- Payment 2 is made by the original due date of the return.
- Only one return-type box is checked and the right identification numbers are entered.
- The payment is separate from any other tax payments.
Sources & verification
- Issuing agency: California Franchise Tax Board
- Official documents: FTB 3893 (PDF) · 2026 Instructions for FTB 3893 (PDF)
- Checked against: FTB 3893 and the 2026 Instructions for Form FTB 3893
- Last verified: October 14, 2026
Spot an error or an out-of-date figure? Tell us and we will check it against the official source.
General information from the official form and its instructions, not advice for your circumstances. See the full disclaimer.
More California Tax Forms forms
- California Form 100 — Corporation Franchise or Income Tax Return 2025-2026
- California Form 540 — Resident Income Tax Return 2025-2026
- California Form 540-ES — Estimated Tax for Individuals
- California Form 540NR — Nonresident or Part-Year Resident Income Tax Return 2025-2026
- California Form 568 — Limited Liability Company Return of Income 2025-2026
- California Form DE 4 — Employee’s Withholding Allowance Certificate
- California FTB 3514 — California Earned Income Tax Credit
- California FTB 3522 — LLC Tax Voucher
- California Schedule CA (540) — California Adjustments, Residents