

What is Form IL-1065?
Quick answer: Form IL-1065 is the Illinois Partnership Replacement Tax Return. A partnership with Illinois base income or loss files it, pays a 1.5% replacement tax after a $1,000 standard exemption, and reports each partner’s share on Schedule B. A partnership can instead elect to pay pass-through entity (PTE) tax of 4.95% of its net income by checking Box I, which gives its partners a credit and relieves most nonresident partners of their own Illinois filing. The return is due the 15th day of the 4th month after year-end, with an automatic 6-month extension.
Illinois partnerships pay a replacement tax on their own base income, separate from the income tax their partners pay. A partnership that does not elect PTE tax must also withhold Illinois income tax on behalf of its nonresident partners (pass-through withholding), and reports that withholding on the return.
The PTE tax election is made on the return itself. Publicly traded partnerships under IRC section 7704 cannot elect, and the Illinois Income Tax Act was amended so the PTE tax no longer has an expiration date.
Key Figures — Form IL-1065 (2025 form; instructions R-07/26)
- Replacement tax: 1.5% of net income (Line 54), after the standard exemption of $1,000 multiplied by Illinois base income over total base income (Line 52).
- PTE tax election: check Box I; the tax is 4.95% of calculated net income (Lines 60 and 61). The partnership then does not complete Schedule K-1-P(3).
- Due date: the 15th day of the 4th month following the close of the tax year.
- Automatic extension: 6 months, with no form required; tax must still be paid by the original due date with Form IL-1065-V or electronically.
- Estimated tax: required if you elect PTE tax and expect total liability above $500, due on the 15th day of the 4th, 6th, 9th and 12th months of the tax year. Other partnerships may prepay voluntarily.
- Tax years covered: the 2025 form is for years ending on or after December 31, 2025 and before December 31, 2026.
Source: the Illinois Department of Revenue, 2025 Form IL-1065 and IL-1065 Instructions (R-07/26). Last verified October 14, 2026.
Who Must File Form IL-1065?
File Form IL-1065 if you are a partnership with base income or loss, as defined in the Illinois Income Tax Act, allocable to Illinois. A partnership organized only to play the Illinois State Lottery does not file.
Combined returns are not allowed. A partnership in a unitary business group cannot file a combined return, but it may have special filing requirements (Schedule UB).
Investment partnerships can elect PTE tax but must still calculate investment partnership withholding; they complete all applicable lines of Schedule B, Section B for each partner.
Partnerships that do not elect PTE tax must withhold on behalf of nonresident partners and report it on Line 59 and Schedule B.
Common trap: completing Schedule K-1-P(3) after electing PTE tax. The instructions say not to complete it if you have elected to pay the pass-through entity tax.
How to File Form IL-1065
- Decide whether to elect PTE tax. If you do, check Box I and complete Lines 60 and 61, and make estimated payments if liability will exceed $500.
- Complete the income steps: income or loss (Step 4), base income (Step 5), allocation to Illinois if multistate (Step 6), net income (Step 7) and net replacement tax (Step 8).
- Complete Schedule B with each partner’s information and Schedules K-1-P as required. Section B, Lines J, K and L cannot be negative.
- Pay with Form IL-1065-V or electronically (MyTax Illinois, credit card or ACH credit) by the original due date.
- File electronically through Modernized e-File or tax software, or mail the return.
- Amend with Form IL-1065-X.
When Is Form IL-1065 Due?
Form IL-1065 is due on or before the 15th day of the 4th month following the close of the tax year. Illinois grants an automatic six-month extension to file, whether or not you request it. An additional extension is granted only if the IRS grants one beyond the Illinois date, and you must attach the approved federal extension. An extension is not an extension of time to pay: replacement tax, pass-through withholding and PTE tax must be paid in full by the original due date, using Form IL-1065-V or an electronic method. Estimated payments for PTE tax filers fall on the 15th day of the 4th, 6th, 9th and 12th months of the tax year.
Where to Mail Form IL-1065
If a payment is enclosed, mail Form IL-1065 to: Illinois Department of Revenue, PO Box 19053, Springfield IL 62794-9053. If no payment is enclosed, mail it to: Illinois Department of Revenue, PO Box 19031, Springfield IL 62794-9031.
How to Complete Form IL-1065 Line by Line
Step 1 — Identify Your Partnership (Boxes A–J)
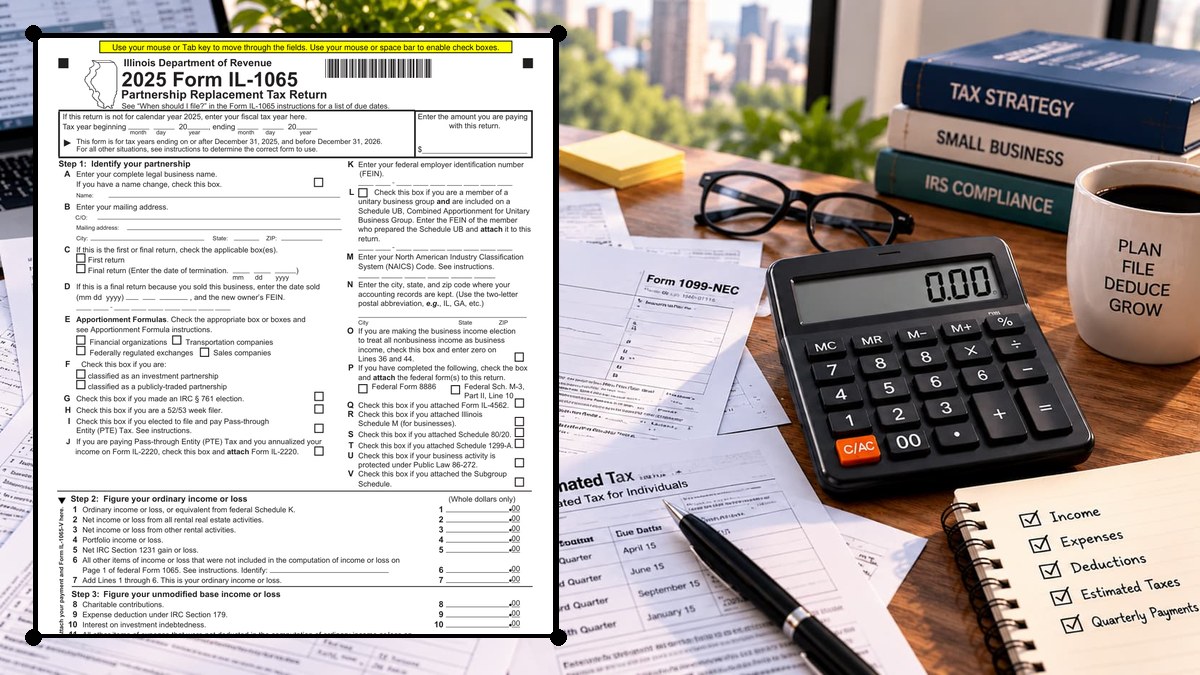
Enter the legal name, address, FEIN and other identifying information. Box I is the PTE tax election: check it if you elect to file and pay PTE tax. Box J is checked, with Form IL-2220 attached, if you annualized income. Other boxes indicate attached schedules, apportionment formulas and whether this is a first or final return.
Steps 4–5 (Lines 14–35) — Income and Base Income
Start from federal partnership income and make Illinois additions: the special depreciation addition (Line 17), related-party expenses (Line 18), distributive share of additions (Line 19), guaranteed payments to partners from federal Form 1065 (Line 20), the amount of loss distributable to a partner subject to replacement tax (Line 21) and other additions (Line 22).
| Line | What to enter |
|---|---|
| Line 23 | Income or loss. Subtractions (Lines 24–33) include exempt federal interest, the personal service income allowance (Line 26) and the share of income distributable to a partner subject to replacement tax (Line 27). |
| Line 35 | Base income or loss. |
Step 6 (Lines 36–46) — Income Allocable to Illinois
Complete this step only if the partnership does business inside and outside Illinois. Business income is apportioned by the sales factor:
| Line | What to enter |
|---|---|
| Line 40 | Sales everywhere. |
| Line 41 | Sales inside Illinois. |
| Line 42 | The apportionment factor. |
| Line 43 | Business income apportionable to Illinois. |
| Line 46 | Base income or loss allocable to Illinois. |
Steps 7–8 (Lines 47–58) — Net Income and Replacement Tax
| Line | What to enter |
|---|---|
| Line 48 | The Illinois net loss deduction (Schedule NLD). |
| Line 52 | The exemption allowance: $1,000 times the fraction of base income allocable to Illinois. |
| Line 53 | Net income. |
| Line 54 | Multiplies Line 53 by 1.5%. |
| Line 55 | Adds recapture of investment credits. |
| Line 57 | Subtracts investment credits (Form IL-477). |
| Line 58 | Net replacement tax. |
Investment partnerships skip Step 8.
Step 9 (Lines 59–64) — Withholding, PTE Income and Tax, and Penalty
| Line | What to enter |
|---|---|
| Line 59 | Pass-through withholding for nonresident partners (Schedule B). |
| Line 60 | Pass-through entity income. |
| Line 61 | PTE tax at 4.95%, both completed only if you elected PTE tax. |
| Line 62 | Adds Lines 58, 59 and 61. |
| Line 63 | The underpayment penalty from Form IL-2220 for electing partnerships above $500 of liability. |
| Line 64 | Totals taxes, withholding, entity tax and penalty. |
Step 10 (Lines 65–68) — Payments, Overpayment and Refund
| Line | What to enter |
|---|---|
| Lines 65–66 | Payments. |
| Line 67 | An overpayment if payments exceed Line 64. |
| Line 68 | The amount credited forward. |
The refund or balance due follows. Schedule B reports each partner’s information, including the PTE tax credit passed through on Line K (each partner’s PTE income times 4.95%) and credits received from other electing entities on Line L.
Common Mistakes to Avoid
- Electing PTE tax but still completing K-1-P(3). It is not completed once you elect.
- Missing PTE estimated payments. Electing partnerships expecting liability over $500 must pay quarterly.
- Assuming the 6-month extension covers payment. Pay by the original due date.
- Filing a combined return for a unitary group. Partnerships cannot, though Schedule UB may apply.
- Using the wrong form year. The 2025 form is for years ending December 31, 2025 through December 30, 2026.
- Negative Schedule B amounts. Lines J, K and L cannot be negative.
Frequently Asked Questions
What is the Illinois partnership replacement tax rate? 1.5% of net income after a $1,000 standard exemption allowance (apportioned).
What is the PTE tax rate? 4.95% of the partnership’s calculated net income, if it elects to pay PTE tax.
When is Form IL-1065 due? The 15th day of the 4th month after the close of the tax year, with an automatic six-month extension.
Can a publicly traded partnership elect PTE tax? No. A publicly traded partnership under IRC section 7704 cannot elect.
Who pays estimated tax? Partnerships that elect PTE tax and expect total liability above $500.
How do I amend? File Form IL-1065-X.
Final Review Before Filing
- The partnership has Illinois base income or loss and is not exempt (such as a lottery-only partnership).
- The PTE tax election decision is made and Box I is checked if electing.
- Schedule B is complete for each partner; K-1-P(3) is not completed if PTE tax is elected.
- The replacement tax and exemption allowance are computed correctly.
- Estimated tax payments are made if PTE tax is elected and liability exceeds $500.
- Payment is made by the original due date.
Sources & verification
- Issuing agency: Illinois Department of Revenue
- Official documents: Form IL-1065 (PDF) · IL-1065 Instructions (PDF)
- Checked against: 2025 Form IL-1065 and IL-1065 Instructions (R-07/26)
- Last verified: October 14, 2026
Spot an error or an out-of-date figure? Tell us and we will check it against the official source.
General information from the official form and its instructions, not advice for your circumstances. See the full disclaimer.
More Illinois Tax Forms forms
- Illinois Form IL-1040 — Individual Income Tax Return 2025-2026
- Illinois Form IL-1040-X — Amended Individual Income Tax Return 2025-2026
- Illinois Form IL-1120 — Corporation Income and Replacement Tax Return 2025-2026
- Illinois Form IL-W-4 — Employee’s and Other Payee’s Illinois Withholding Allowance Certificate
- Illinois Form RUT-50 — Private Party Vehicle Use Tax Transaction Return
- Illinois Schedule ICR — Illinois Credits 2025-2026
- Illinois Schedule NR — Nonresident and Part-Year Resident Computation of Illinois Tax 2025-2026