
What is Form IL-1120?
Quick answer: Form IL-1120 is the Illinois Corporation Income and Replacement Tax Return. A C corporation that has Illinois net income or loss, or is qualified to do business in Illinois and must file a federal return, files it. Illinois charges two taxes on the same net income: a 2.5% replacement tax and a 7.0% income tax. The return is due on the 15th day of the 4th month after year-end (the 3rd month for a June 30 year-end), with an automatic 7-month extension to file, but the tax is still due on the original date.
Illinois starts from federal taxable income (Form 1120, line 30), makes additions and subtractions to reach base income, apportions that income to Illinois using the sales factor if the business operates in more than one state, subtracts any Illinois net loss deduction, and then applies both tax rates to the resulting net income.
S corporations do not use this form: they are subject only to replacement tax and file Form IL-1120-ST. Partnerships file Form IL-1065.
Key Figures — Form IL-1120 (2025 form, R-12/25; instructions R-07/26)
- Replacement tax: 2.5% of net income (Line 40).
- Income tax: 7.0% of net income (Line 45).
- Due date: the 15th day of the 4th month after the close of the tax year; the 15th day of the 3rd month for a June 30 year-end; the 15th day of the 9th month for cooperatives.
- Automatic extension: 7 months (8 months for a June 30 year-end; 7 months for cooperatives), with no form required. It does not extend the time to pay.
- Estimated tax: required if you reasonably expect the Illinois income and replacement tax and surcharge to exceed $400; payments are due on the 15th day of the 4th, 6th, 9th and 12th months of the tax year.
- Tax years covered: the 2025 form is for tax years ending on or after December 31, 2025 and before December 31, 2026; use the 2024 form for earlier years.
- New for 2025: Illinois adopts the “Finnigan” method of apportionment for unitary businesses for tax years ending on or after December 31, 2025, and the expiration date of the pass-through entity tax was removed.
Source: the Illinois Department of Revenue, 2025 Form IL-1120 and IL-1120 Instructions (R-07/26). Last verified October 14, 2026.
Who Must File Form IL-1120?
File Form IL-1120 if you are a corporation that has net income or loss as defined in the Illinois Income Tax Act, or that is qualified to do business in Illinois and must file a federal income tax return, whether or not it has net income. A limited liability company that files as a corporation for federal purposes is treated as a corporation.
Unitary business groups use Schedule UB for combined apportionment. Political organizations and homeowners’ associations that file federal Form 1120-POL or 1120-H, cooperatives filing 1120-C and settlement funds filing 1120-SF also file Form IL-1120.
Who does not file this form: S corporations (they file Form IL-1120-ST), REMICs, and organizations exempt under IRC section 501(a), although unrelated business taxable income is reported on Form IL-990-T.
E-filing mandate: any taxpayer required to file its federal return electronically must file its Illinois return electronically.
Common trap: forgetting that Illinois charges both taxes. Replacement tax (2.5%) and income tax (7.0%) are computed on the same net income and added together on Line 58.
How to File Form IL-1120
- Register with the Department (MyTax Illinois or Form REG-1) before filing. Your identification numbers are your FEIN and your Illinois account number.
- Start from your federal return. Enter federal taxable income from federal Form 1120, Line 30 on Line 1 and attach a copy of the federal return.
- Complete the steps in order: income or loss (Step 2), base income (Step 3), apportionment to Illinois if needed (Step 4), net income (Step 5), replacement tax (Step 6), income tax (Step 7) and refund or balance due (Step 8).
- Pay electronically. Use MyTax Illinois, a credit card at tax.illinois.gov/payments/creditcard, or an ACH credit. If you must mail a payment, complete Form IL-1120-V and write your FEIN, the tax year ending and “IL-1120-V” on the check.
- Sign. The president, vice president, treasurer or another authorized officer must sign; a paid preparer must also sign and enter a PTIN.
- To correct a filed return, file Form IL-1120-X, not another IL-1120.
When Is Form IL-1120 Due?
Form IL-1120 is due on or before the 15th day of the 4th month following the close of the tax year, which matches the federal due date. A corporation with a June 30 year-end files by the 15th day of the 3rd month, and a cooperative by the 15th day of the 9th month. Illinois grants an automatic extension to file of 7 months (8 for a June 30 year-end) whether or not you ask. An additional extension is granted only if the IRS grants one beyond the Illinois date, equal to the federal extension plus one month, and you attach the federal approval. The tax itself must be paid in full by the original due date; interest runs from the day after that date. If you must make quarterly estimated payments, they are due on the 15th day of the 4th, 6th, 9th and 12th months of the tax year.
Where to Mail Form IL-1120
If a payment is enclosed, mail Form IL-1120 to: Illinois Department of Revenue, PO Box 19038, Springfield IL 62794-9038. If no payment is enclosed, mail it to: Illinois Department of Revenue, PO Box 19048, Springfield IL 62794-9048. Most corporations file electronically.

How to Complete Form IL-1120 Line by Line
Step 1 — Identify Your Corporation (Boxes A–Y)
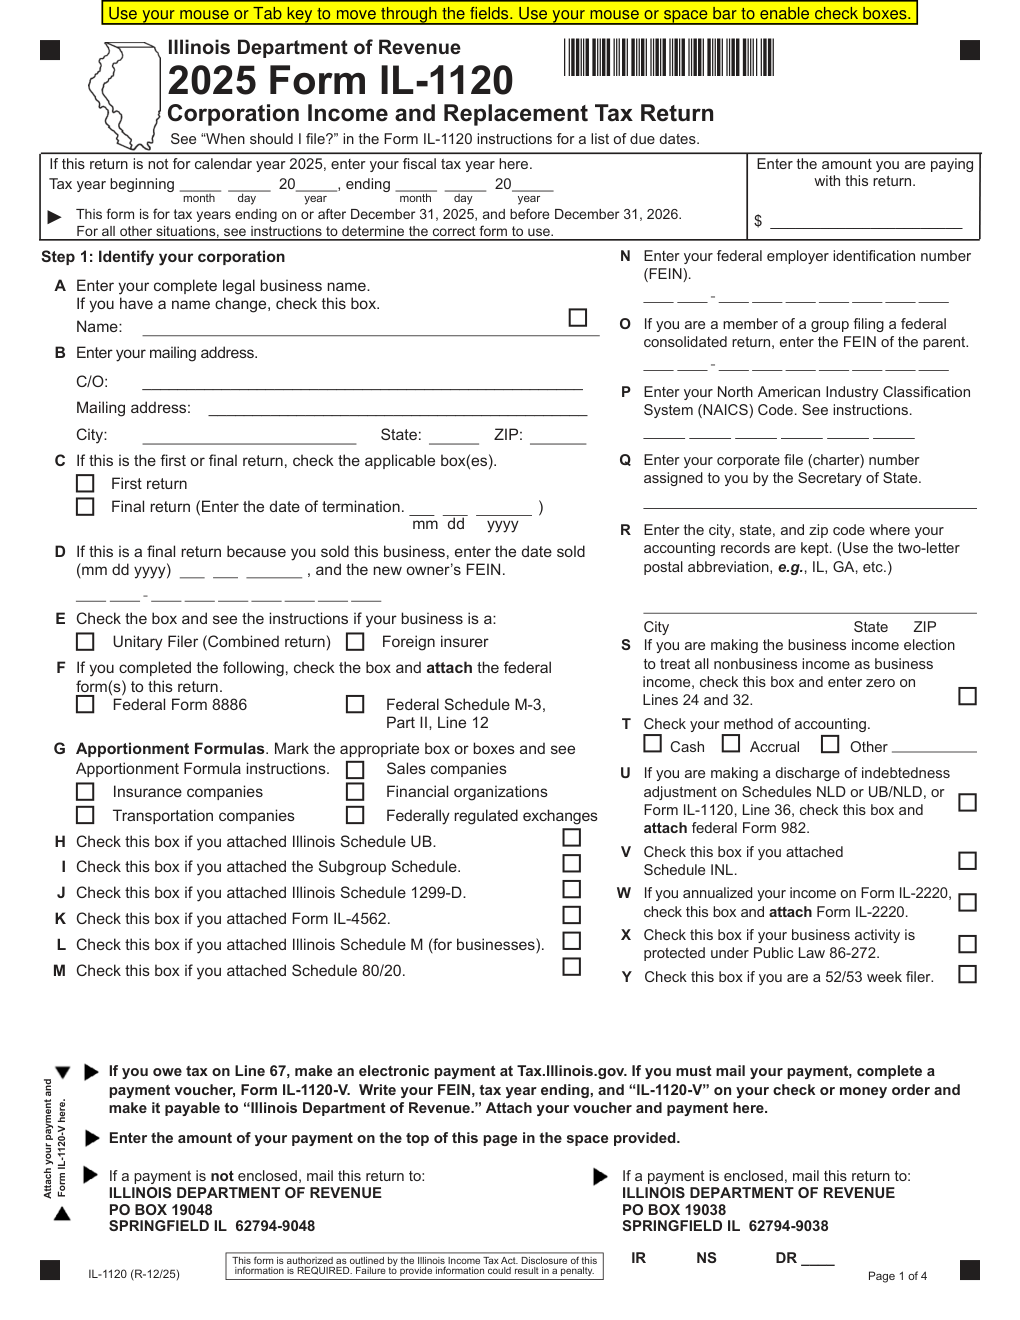
Enter the legal name, mailing address, FEIN (Box N), the parent’s FEIN if you are in a federal consolidated group (Box O), NAICS code (Box P) and Secretary of State charter number (Box Q). Check boxes for a first or final return, unitary filers, foreign insurers, and the apportionment formula that applies (sales, insurance, financial organizations, transportation, federally regulated exchanges). Box S is the business income election to treat all nonbusiness income as business income, Box T the accounting method, Box W an annualized income election on Form IL-2220, and Box X Public Law 86-272 protection.
Step 2 (Lines 1–9) — Figure Your Income or Loss
| Line | What to enter |
|---|---|
| Line 1 | Federal taxable income from federal Form 1120, Line 30. |
| Line 2 | Adds back the net operating loss deduction from federal Line 29a (it cannot be negative). |
| Line 3 | Adds state, municipal and other interest income excluded from Line 1. |
| Line 4 | Adds Illinois income and replacement tax and surcharge deducted federally. |
| Line 5 | The Illinois special depreciation addition (Form IL-4562). |
| Line 6 | Related-party expenses (Schedule 80/20). |
| Line 7 | Distributive share of additions from Schedules K-1-P or K-1-T. |
| Line 8 | Other additions (Schedule M). |
| Line 9 | Adds Lines 1 through 8. |
Step 3 (Lines 10–23) — Figure Your Base Income or Loss
Subtractions include interest from U.S. Treasury and other exempt federal obligations (Line 10), River Edge Redevelopment Zone and High Impact Business subtractions (Lines 11–14, Schedule 1299-B), the contribution subtraction (Line 15), foreign dividends (Line 17, Schedule J), the Illinois special depreciation subtraction (Line 18) and related-party expenses (Line 19). Line 23 is base income or loss.
Step 4 (Lines 24–34) — Income Allocable to Illinois
Complete this step only if the corporation does business inside and outside Illinois. Nonbusiness income or loss is allocated on Schedule NB (Line 24), and business income (Line 27) is apportioned using sales:
| Line | What to enter |
|---|---|
| Line 28 | Total sales everywhere. |
| Line 29 | Total sales inside Illinois. |
| Line 30 | The apportionment factor (Line 29 divided by Line 28, six decimal places). |
| Line 31 | Business income apportionable to Illinois. |
| Line 34 | Base income allocable to Illinois. |
A unitary business group completes Schedule UB, and the new Finnigan rules apply to the sales factor.
Step 5 (Lines 35–39) — Net Income
| Line | What to enter |
|---|---|
| Line 35 | Carries base income from Step 3 (Line 23) or Step 4 (Line 34). |
| Line 36 | A discharge of indebtedness adjustment (attach federal Form 982). |
| Line 37 | Adjusted base income. |
| Line 38 | The Illinois net loss deduction (Schedule NLD or UB/NLD); enter zero if Line 37 is zero or negative. |
| Line 39 | Net income. |
Steps 6–7 (Lines 40–49) — Replacement Tax and Income Tax
| Line | What to enter |
|---|---|
| Line 40 | Multiplies Line 39 by 2.5% for replacement tax. |
| Line 41 | Adds recapture of investment credits (Schedule 4255). |
| Line 43 | Subtracts investment credits (Form IL-477). |
| Line 44 | Replacement tax after credits. |
| Line 45 | Multiplies Line 39 by 7.0% for income tax. |
| Line 46 | Total of the lines above. |
| Line 48 | Subtracts income tax credits (Schedule 1299-D). |
| Line 49 | Income tax after credits. |
Neither line can be negative.
Step 8 (Lines 50–67) — Refund or Balance Due
Lines 50–55 apply any foreign insurer reductions to get net replacement tax (Line 52) and net income tax (Line 55).
| Line | What to enter |
|---|---|
| Lines 56–57 | Add the Compassionate Use of Medical Cannabis Program Act surcharge and the gaming licensee asset-sale surcharge. |
| Line 58 | Totals taxes and surcharges. |
| Line 59 | The underpayment of estimated tax penalty (Form IL-2220). |
| Line 60 | Total taxes, surcharges and penalty. |
| Lines 61–62 | Payments. |
| Line 63 | An overpayment. |
| Line 64 | The amount credited forward. |
| Line 65 | The refund (direct deposit on Line 66). |
| Line 67 | The tax due. |
Common Mistakes to Avoid
- Using the wrong year’s form. The 2025 form is for tax years ending on or after December 31, 2025 and before December 31, 2026; using the wrong form delays processing.
- Filing IL-1120 for an S corporation. It files Form IL-1120-ST.
- Treating the extension as a payment extension. Tax is due on the original date.
- Skipping the federal return attachment. Attach a copy of the federal return with Line 1.
- Sending a computer printout instead of the IDOR form. Only approved forms and approved software output are accepted.
- Filing a second IL-1120 to correct errors. Use Form IL-1120-X.
- Missing estimated payments. A liability expected to exceed $400 requires quarterly estimated payments.
Frequently Asked Questions
What are the Illinois corporate tax rates? A 2.5% replacement tax and a 7.0% income tax, both applied to net income.
When is Form IL-1120 due? The 15th day of the 4th month after year-end (3rd month for a June 30 year-end).
Is there an automatic extension? Yes, 7 months (8 months for a June 30 year-end), granted whether or not you request it, but tax is still due on the original date.
Do S corporations file IL-1120? No. They file Form IL-1120-ST and pay replacement tax only.
Do I need to attach my federal return? Yes, attach a copy of the federal return with Line 1.
How do I amend an Illinois corporate return? File Form IL-1120-X for each tax year you want to change.
Final Review Before Filing
- This is the right form for the corporation (not an S corporation or a partnership).
- Line 1 matches federal Form 1120, Line 30, and the federal return is attached.
- Apportionment (Step 4) is completed if the business operates in more than one state.
- Both the 2.5% replacement tax and 7.0% income tax are computed on Line 39.
- Estimated payments are included on Line 61 and the penalty (Form IL-2220) on Line 59 if applicable.
- An authorized officer signed the return.
- Payment is made electronically, or Form IL-1120-V accompanies the check.
Sources & verification
- Issuing agency: Illinois Department of Revenue
- Official documents: Form IL-1120 (PDF) · IL-1120 Instructions (PDF)
- Checked against: 2025 Form IL-1120 (R-12/25) and IL-1120 Instructions (R-07/26)
- Last verified: October 14, 2026
Spot an error or an out-of-date figure? Tell us and we will check it against the official source.
General information from the official form and its instructions, not advice for your circumstances. See the full disclaimer.
More Illinois Tax Forms forms
- Illinois Form IL-1040 — Individual Income Tax Return 2025-2026
- Illinois Form IL-1040-X — Amended Individual Income Tax Return 2025-2026
- Illinois Form IL-1065 — Partnership Replacement Tax Return 2025-2026
- Illinois Form IL-W-4 — Employee’s and Other Payee’s Illinois Withholding Allowance Certificate
- Illinois Form RUT-50 — Private Party Vehicle Use Tax Transaction Return
- Illinois Schedule ICR — Illinois Credits 2025-2026
- Illinois Schedule NR — Nonresident and Part-Year Resident Computation of Illinois Tax 2025-2026