What is Form M3?
Quick answer: Form M3 is the Minnesota Partnership Return. Every entity required to file federal Form 1065 that has Minnesota gross income files it. Partners pay income tax on their shares, but the partnership pays the minimum fee and, if it elects, the pass-through entity (PTE) tax on Schedule PTE (9.85% on the 2025 schedule). The return is due on the same date as the federal return, with an automatic six-month extension if the tax payable is paid by the regular due date.
Minnesota taxes the entire share of partnership income to the partner, whether or not it is distributed. The partnership itself pays only the minimum fee and any entity-level taxes: PTE tax, composite income tax for nonresident partners who elect it, or withholding for nonresident individual partners.
S corporations use Form M8. A single-member LLC files the return that matches its federal classification.
Key Figures — 2025 Form M3 and 2025 Partnership Form M3 Instructions
- Who files: all entities required to file federal Form 1065 that have Minnesota gross income.
- Minimum fee: applies if the sum of Minnesota-source property, payroll and sales or receipts is at least $1,250,000; exempt if more than 80% of income is from farming. It is determined on M3A.
- Due date: the same date as the federal return and payment.
- Extension: automatic six months if tax payable is paid by the regular due date; a longer federal extension extends the state date. Pay any extension tax by the regular due date.
- Estimated tax: quarterly payments are required when the sum of estimated minimum fee, nonresident withholding, PTE tax and composite income tax, less credits, is $500 or more; not required in the first year of Minnesota filing. Required annual payment: the lesser of 90% of the current year’s liability or 100% of the prior year’s.
- PTE tax: check the PTE box, complete Schedule PTE and enter the tax on line 2; the election is made by the due date or extended due date. Schedule PTE (2025) multiplies the computed base by 9.85%.
- Mail to: Minnesota Partnership Tax, Mail Station 1760, 600 N. Robert St., St. Paul MN 55146-1760.
Source: the Minnesota Department of Revenue, 2025 Form M3, Schedule PTE and the 2025 Partnership Form M3 Instructions. Last verified October 14, 2026.
Who Must File Form M3?
File Form M3 if you are required to file federal Form 1065 and have Minnesota gross income. The partners include their shares on their own returns; the minimum fee is paid by the entity.
The PTE election is available to partnerships, LLCs and S corporations with one or more qualifying owners. Single-member LLCs that are not taxed as S corporations cannot file Schedule PTE. The election must be made by the due date or extended due date of the entity’s return, and the entity provides Schedule KPI to all partners.
Nonresident partners can participate in composite income tax (reported on line 3, with Schedule KPI) or have Minnesota income tax withheld (line 4, with Forms AWC where applicable). Nonresident individual partners whose entity-level tax fulfills their filing requirement may not need to file Form M1, unless they owe net investment income tax (Schedule NIIT) or have installment-sale gains.
Special situations: a final return, an LLC, installment sales of pass-through assets or interests, and tax position disclosure (Form TPD) are marked at the top of the return.
Common trap: assuming the six-month extension also extends payment. The extension is for filing only; extension payments are due on the regular due date.
How to File Form M3
- Complete federal Form 1065 and Schedules K and K-1, and include a complete copy with the Minnesota return.
- Complete M3A (apportionment and minimum fee), then Form M3, then Schedule KPI for each partner.
- If electing PTE tax, complete Schedule PTE and Schedule PTE-RP, check the PTE box and enter the tax on line 2.
- Make estimated or extension payments electronically, by credit card or by check with a voucher created on the Department’s website.
- E-file or mail the return to the address below. Amend with Form M3X.
When Is Form M3 Due?
The Minnesota return and payment are due on the same date as the federal return and payment; if that date falls on a weekend or holiday, an electronic payment or postmark on the next business day is timely. All partnerships receive an automatic six-month extension to file if the tax payable for the year is paid by the regular due date, and the state date follows a longer federal extension. Four kinds of payments exist: extension, estimated tax, tax return and amended return payments.
Where to Mail Form M3
If you do not use the mailing label, mail your forms, with a complete copy of your federal Form 1065, Schedules K and K-1 and other federal schedules, to: Minnesota Partnership Tax, Mail Station 1760, 600 N. Robert St., St. Paul MN 55146-1760.
How to Complete Form M3 Line by Line
Top of the Return — Identification and Special Boxes
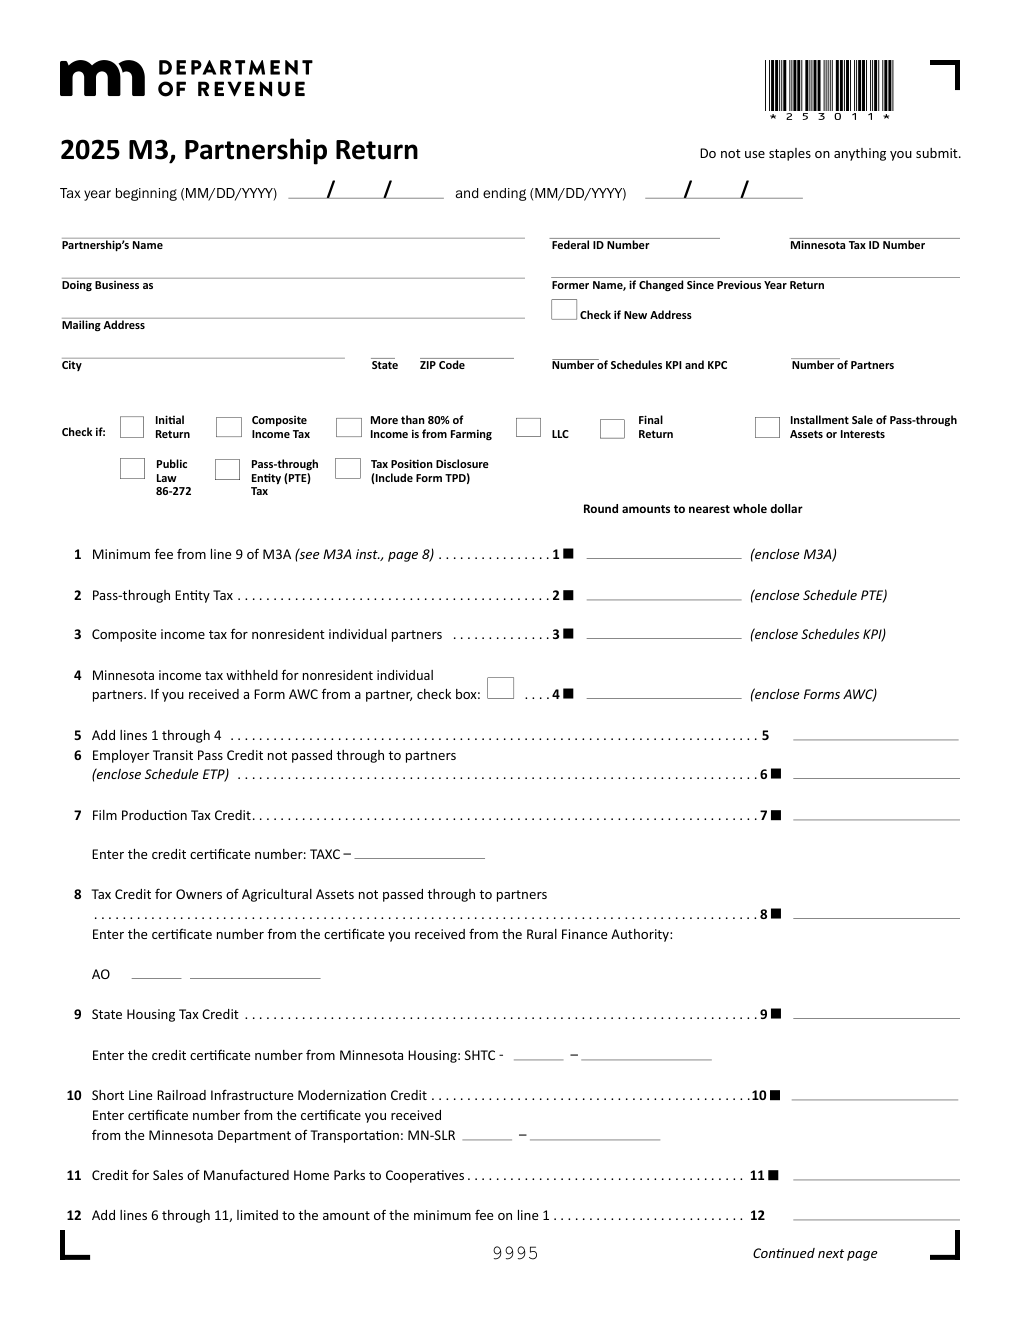
Enter the partnership’s name, federal ID number and Minnesota tax ID. Boxes at the top mark the pass-through entity tax election, more than 80% of income from farming, tax position disclosure (include Form TPD), a final return, LLC, and an installment sale of pass-through assets or interests.
Lines 1–5 — Minimum Fee and Entity-Level Taxes
| Line | What to enter |
|---|---|
| Line 1 | The minimum fee from line 9 of M3A. |
| Line 2 | The pass-through entity tax (enclose Schedule PTE). |
| Line 3 | Composite income tax for nonresident individual partners who elect to participate (enclose Schedules KPI). |
| Line 4 | Minnesota income tax withheld for nonresident individual partners (enclose Forms AWC if you received them). |
| Line 5 | Adds lines 1 through 4. |
Lines 6–12 — Credits Limited to the Minimum Fee
| Line | What to enter |
|---|---|
| Line 6 | (Schedule ETP). |
| Lines 7–11 | List credits not passed through to partners: the film production tax credit, tax credit for owners of agricultural assets, State Housing Tax Credit (with the Minnesota Housing certificate number), Short Line Railroad Infrastructure Modernization Credit (with the MnDOT certificate number) and the credit for sales of manufactured home parks to cooperatives. |
| Line 12 | Adds lines 6 through 11, limited to the minimum fee on line 1. |
Lines 13–24 — Tax Due, Penalty, Interest and Refund
| Line | What to enter |
|---|---|
| Line 13 | Subtracts line 12 from line 5. |
| Line 14 | An enterprise zone credit not passed through. |
| Line 15 | Estimated and extension payments for 2025. |
| Line 17 | Tax due. |
| Lines 18–20 | Add the penalty, interest and the additional charge for underpayment of estimated tax (Schedule EST). |
| Line 21 | The amount due, with the payment method checked. |
| Line 22 | An overpayment. |
| Line 23 | The amount credited to 2026 estimated tax. |
| Line 24 | The refund. |
M3A — Apportionment and Minimum Fee
Every partnership completes M3A to determine its Minnesota-source income and minimum fee. It lists property (inventory, buildings and machinery, land and capitalized rents), payroll and sales inside Minnesota and everywhere, and computes the factors. The minimum fee on line 9 is carried to line 1 of Form M3.
Common Mistakes to Avoid
- Forgetting the federal attachments. Include a complete copy of federal Form 1065 and Schedules K and K-1.
- Missing Schedule PTE when electing. The election requires Schedule PTE and the PTE box.
- Not paying the extension tax. The extension covers filing only.
- Skipping estimated payments when the entity-level taxes will reach $500.
- Using M3 for an S corporation. It files Form M8.
- Not providing Schedule KPI to all partners after electing PTE tax.
Frequently Asked Questions
Who files Form M3? Entities required to file federal Form 1065 that have Minnesota gross income.
What is the minimum fee? A fee that applies when Minnesota property, payroll and sales total at least $1,250,000, determined on M3A.
Is there an extension? Yes, an automatic six-month extension to file if the tax payable is paid by the regular due date.
How does the PTE election work? Check the PTE box, complete Schedule PTE and enter the tax on line 2, by the due date or extended due date.
What is the PTE tax rate? The 2025 Schedule PTE multiplies the computed amount by 9.85%.
Where do I mail Form M3? Minnesota Partnership Tax, Mail Station 1760, 600 N. Robert St., St. Paul MN 55146-1760.
Final Review Before Filing
- Federal Form 1065 and K-1s are complete and a complete copy is attached.
- M3A is complete and the minimum fee is on line 1.
- Schedule PTE and the PTE box are completed if electing.
- Composite tax and withholding for nonresident partners are on lines 3 and 4.
- Schedule KPI is prepared for each partner.
- Extension and estimated payments are made by the regular due date.
Sources & verification
- Issuing agency: Minnesota Department of Revenue
- Official documents: Form M3 (PDF) · 2025 M3 instructions (PDF)
- Checked against: 2025 Form M3, Schedule PTE and the 2025 Partnership Form M3 Instructions
- Last verified: October 14, 2026
Spot an error or an out-of-date figure? Tell us and we will check it against the official source.
General information from the official form and its instructions, not advice for your circumstances. See the full disclaimer.