What is Form M4?
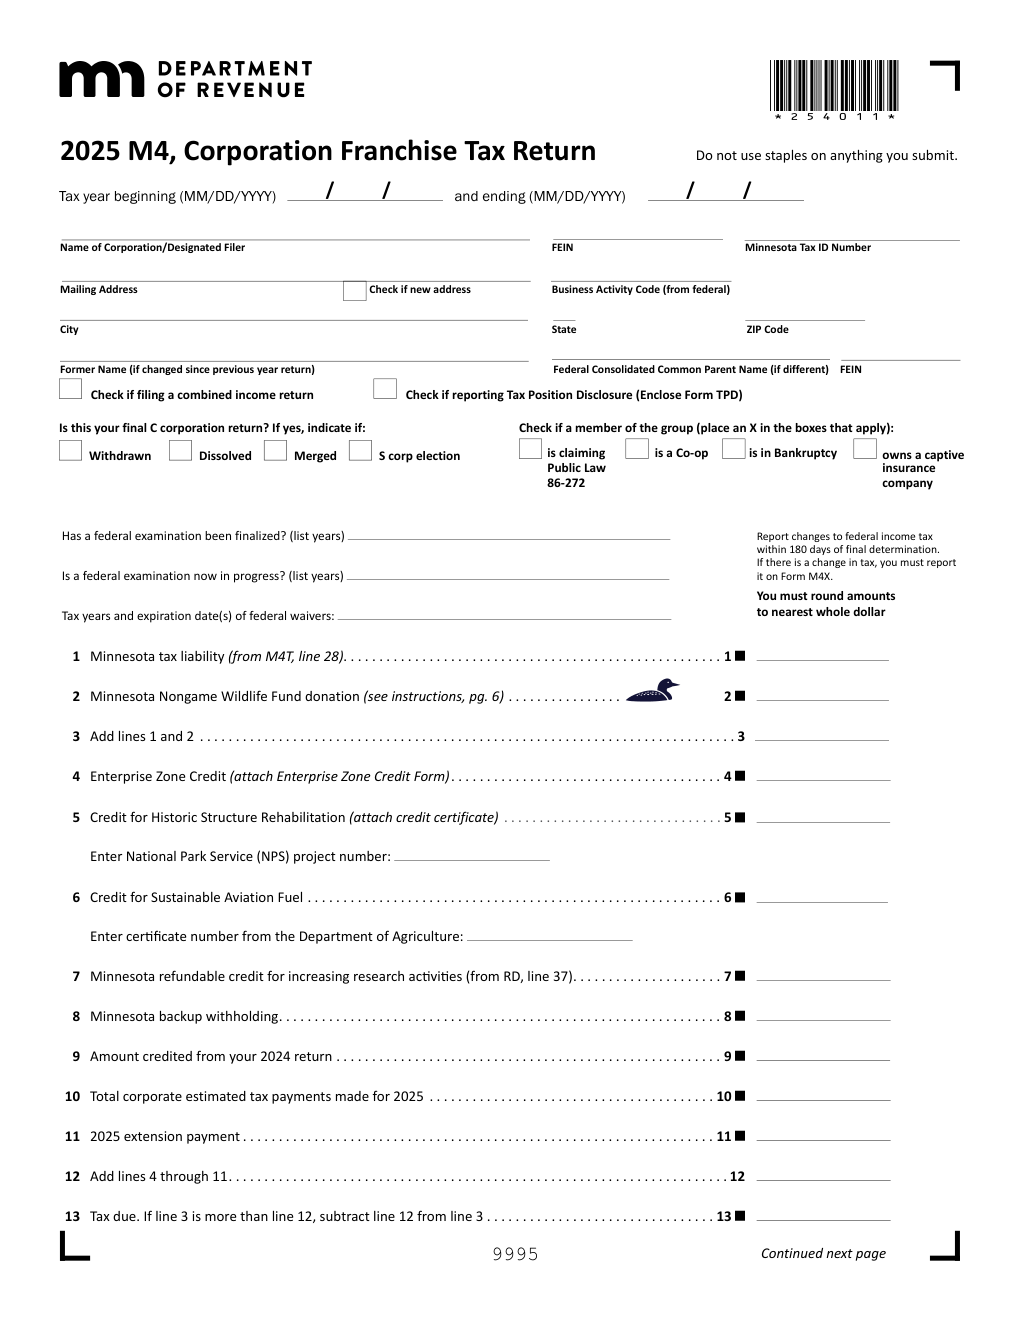
Quick answer: Form M4 is the Minnesota Corporation Franchise Tax Return. Corporations must file a Minnesota return if they transact business or own property in Minnesota, regardless of where they are incorporated. The regular tax is 9.8% of Minnesota taxable income, plus a minimum fee of $260 to $12,540 for corporations with Minnesota property, payroll and sales of at least $1,250,000. The return is due on the same date as the federal return, with an automatic 7-month filing extension (tax is still due on the regular date).
The M4 is a package: the summary page (M4), the income calculation (M4I), the apportionment factor and minimum fee (M4A) and the tax calculation (M4T). Minnesota starts from federal taxable income, adds and subtracts state modifications, apportions income using a sales factor and applies the corporate rate.
S corporations do not file Form M4: they file Form M8. Exempt organizations with unrelated business income file Form M4NP.
Key Figures — 2025 Form M4 series and 2025 Minnesota Corporation Franchise Tax Instructions
- Regular tax: 9.8% of taxable income (M4T, line 10), plus any alternative minimum tax.
- Minimum fee (by Minnesota property, payroll and sales; M4A line 11): under $1,250,000 none; $1,250,000–$2,509,999 $260; $2,510,000–$12,539,999 $750; $12,540,000–$25,069,999 $2,510; $25,070,000–$50,139,999 $5,020; $50,140,000 or more $12,540.
- Due date: the due date of the federal return; cooperative associations (other than IRC 521) file by the 15th day of the 9th month.
- Extension: automatic 7 months with no form required; a longer federal extension extends the state date. It is a filing extension only.
- Estimated tax: if estimated tax is more than $500, quarterly payments are required; corporations that paid $10,000 or more in estimated tax in the 12 months ending June 30 must pay electronically.
- Penalties: 6% of unpaid tax if less than 90% of total tax is paid by the regular due date; 5% for filing after the extended due date; an additional 5% if filed after the regular due date with an unpaid balance.
- NOL: the deduction is limited to 70% of taxable net income (line 5).
Source: the Minnesota Department of Revenue, 2025 Form M4 and 2025 Minnesota Corporation Franchise Tax Instructions. Last verified October 14, 2026.
Who Must File Form M4?
File Form M4 if you are a corporation (other than an S corporation) that transacts business or owns property in Minnesota, whatever your state of incorporation.
Unitary businesses file a combined return under a designated filer, and payments must be made under the designated filer.
Other forms: S corporations filing federal Form 1120-S file Form M8, nonresident entertainers file Form ETR, and exempt organizations with unrelated business income, farmers’ cooperatives filing Form 1120-C, homeowner associations (Form 1120-H) and political organizations (Form 1120-POL) file Form M4NP.
Not required to file: REMICs and qualifying unit investment trusts. Captive insurance companies that qualify are not part of the Minnesota combined group.
Common trap: treating the extension as a payment extension. The automatic 7-month extension covers filing only; tax not paid by the regular due date is subject to penalties and interest.
How to File Form M4
- Complete your federal return first (Form 1120 and schedules) and have your seven-digit Minnesota tax ID.
- Complete M4I (income calculation), M4A (apportionment and minimum fee), M4T (tax calculation) and then the M4 summary.
- Attach the required federal returns and schedules; the return is incomplete without them. Do not staple or tape enclosures.
- Pay. Pay electronically or by check using the voucher created on the Department’s website. Extension payments use the same methods.
- E-file or mail using the mailing label on page 16 of the instructions.
- To amend, file Form M4X, within 180 days after the IRS notified you of a change or after you filed your federal amended return.
When Is Form M4 Due?
Returns, including short-year returns, are due by the due date of the federal income tax return. The U.S. postmark date counts as the filing date, and a weekend or holiday moves the due date to the next business day. All corporations get an automatic seven-month extension to file Form M4 without submitting a form; if the IRS grants a longer extension, the state date follows. The extension is for filing only, so pay any tax by the regular due date. Quarterly estimated payments are required when estimated tax is more than $500.
Where to Mail Form M4
Mail Form M4 and all completed Minnesota and federal forms and schedules using the label on page 16 of the instructions: Minnesota Revenue, Mail Station 1250, 600 N. Robert Street, St. Paul MN 55146-1250.
How to Complete Form M4 Line by Line
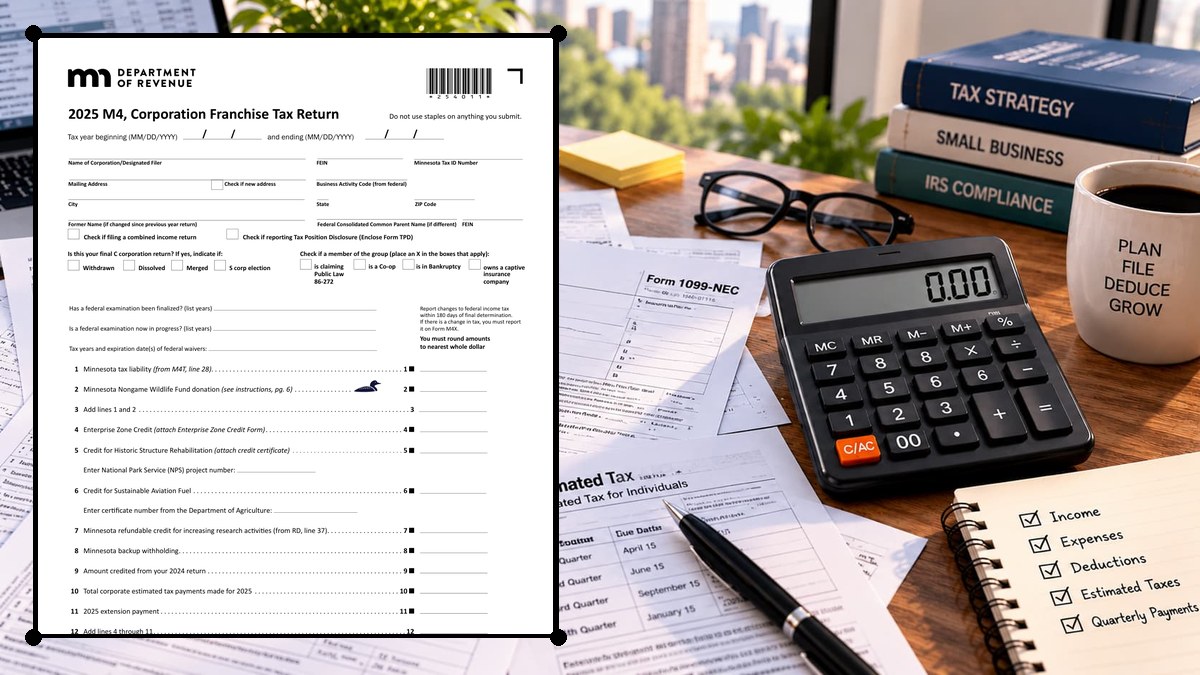
M4 Summary Page — Identification, Income and Tax
Enter the corporation’s name, FEIN and Minnesota tax ID, and mark special boxes (such as combined group, co-op or final return). Line 1 carries Minnesota income from line 9 of Form M4I in each column. The summary pulls the tax liability from M4T, applies credits, estimated payments and backup withholding (line 8), and shows penalties (line 14) and interest (line 15).
M4I — Income Calculation
M4I starts with federal taxable income and applies Minnesota additions (such as the federal deduction for taxes based on net income and the minimum fee, line 2a) and subtractions (such as exempt interest, capital losses and the new employee retention credit subtraction on line 4n). Line 8 reports nonapportionable income and line 9 is Minnesota apportionable income.
M4A — Apportionment and Minimum Fee
M4A computes the apportionment factor from sales and also determines the minimum fee from
| Line | What to enter |
|---|---|
| Line 11 | (Minnesota property, payroll and sales) using the table in the Key Figures. |
| Line 12 | The fee. |
The fee is in addition to the regular tax and the alternative minimum tax. Regulated investment companies and certain other entities are exempt, and a corporation protected by Public Law 86-272 with no Minnesota filing requirement does not pay it.
M4T — Tax Calculation
| Line | What to enter |
|---|---|
| Lines 1–3 | Apply the apportionment factor to Minnesota apportionable income. |
| Lines 4a and 4b | Add Minnesota nonapportionable income and nonunitary partnership income. |
| Line 5 | Taxable net income. |
| Line 6 | The NOL deduction (limited to 70% of line 5). |
| Line 8 | The dividends-received deduction. |
| Line 9 | Taxable income. |
| Line 10 | Multiplies line 9 by 0.098. |
| Lines 11–15 | Add alternative minimum tax and subtract the AMT credit and the nonrefundable research credit. |
| Line 16 | Adds the minimum fee from M4A. |
| Line 17 | Tax liability by corporation. |
Penalties, Interest and Payment Method
A penalty of 6% of the unpaid tax applies if you do not pay at least 90% of your total tax by the regular due date. A 5% late-filing penalty applies if you file after the extended due date and owe tax, and an additional 5% applies when you file after the regular due date with a balance due that is not paid. Interest is calculated on the remaining balance. If you do not pay electronically when required, an additional penalty applies.
Common Mistakes to Avoid
- Forgetting the minimum fee. It applies in addition to the regular tax once Minnesota property, payroll and sales reach $1,250,000.
- Skipping the federal attachments. The return is incomplete without them.
- Assuming the extension covers payment. Pay by the regular due date.
- Deducting more NOL than 70% of line 5.
- Missing electronic payment rules. Estimated payments of $10,000 or more trigger mandatory electronic payment.
- Filing M4 for an S corporation. It files Form M8.
Frequently Asked Questions
What is the Minnesota corporate franchise tax rate? 9.8% of taxable income, plus alternative minimum tax and the minimum fee where applicable.
Who must file Form M4? Corporations that transact business or own property in Minnesota, other than S corporations.
What is the minimum fee? $260 to $12,540 depending on Minnesota property, payroll and sales, with no fee below $1,250,000.
When is Form M4 due? On the due date of the federal return, with an automatic seven-month extension to file.
How do I amend? File Form M4X.
Where do I mail it? Minnesota Revenue, Mail Station 1250, 600 N. Robert Street, St. Paul MN 55146-1250.
Final Review Before Filing
- The corporation does business or owns property in Minnesota and is not an S corporation.
- The federal return and required schedules are attached.
- M4I, M4A and M4T are complete and the minimum fee matches the table.
- The NOL deduction does not exceed 70% of line 5.
- Estimated and extension payments are accounted for.
- The return is filed by the federal due date or the 7-month extension, and tax is paid by the regular due date.
Sources & verification
- Issuing agency: Minnesota Department of Revenue
- Official documents: Form M4 series (PDF) · 2025 M4 instructions (PDF)
- Checked against: 2025 Form M4 series and the 2025 Minnesota Corporation Franchise Tax Instructions
- Last verified: October 14, 2026
Spot an error or an out-of-date figure? Tell us and we will check it against the official source.
General information from the official form and its instructions, not advice for your circumstances. See the full disclaimer.