
What is Form DR-15?
Quick answer: Form DR-15 is the Florida Sales and Use Tax Return that registered dealers file for every reporting period, even when no tax is due. The general state sales tax rate is 6%, plus a county discretionary sales surtax where one applies. Returns and payments are due on the 1st and late after the 20th of the month following the reporting period. Businesses that paid $5,000 or more in sales and use tax in the prior state fiscal year must file and pay electronically, and those who file and pay electronically on time can take a collection allowance. Sales tax on commercial rentals was repealed effective October 1, 2025.
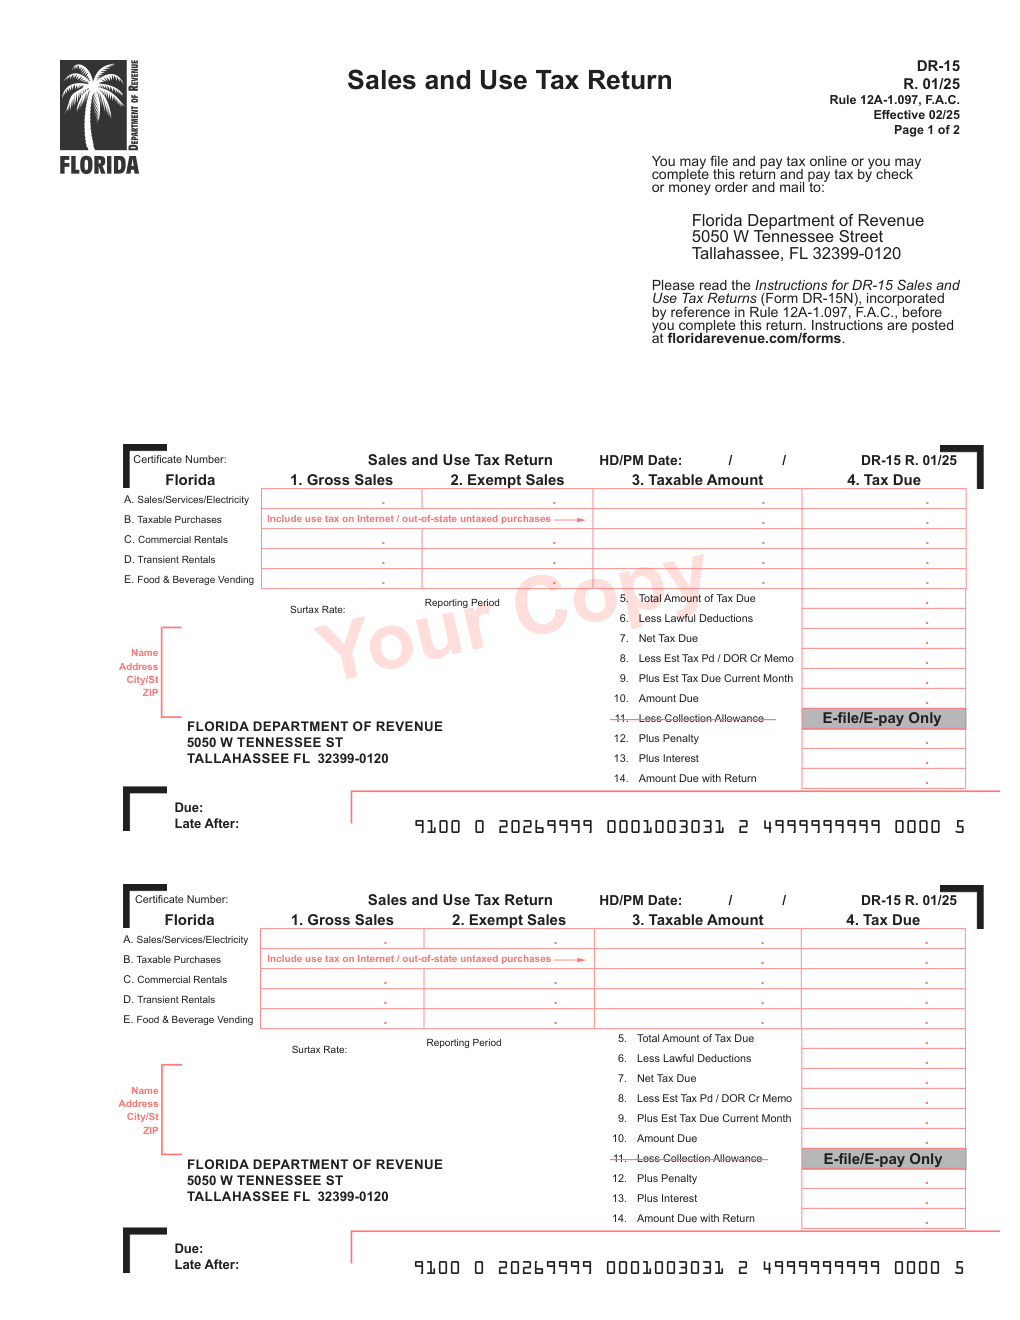
A dealer collects Florida sales tax and surtax from customers and passes it to the Department of Revenue on the DR-15. The return is organized by type of transaction: sales, services and electricity on Line A, use tax on purchases on Line B, commercial rentals on Line C, transient rentals on Line D and food and beverage vending on Line E.
Businesses that don’t have complex activities may qualify for the simpler DR-15EZ. Anyone who is new to sales tax must first register with Form DR-1 to get a certificate number.
Key Figures — Form DR-15 (R. 01/25) and DR-15N (R. 10/25)
- State sales tax rate: 6%; most counties add a discretionary sales surtax, which you report with the tax on Lines A through E.
- Due date: due the 1st, late after the 20th of the month after the period. If the 20th is a weekend or holiday, the next business day.
- Electronic filing: required if you paid $5,000 or more in sales and use tax in the state fiscal year (July 1 to June 30) before the calendar year.
- Collection allowance: 2.5% of the first $1,200 of the Amount Due, up to $30, only for on-time electronic filing and payment.
- Estimated tax: required every month if you paid $200,000 or more in the prior fiscal year; the estimate is 60% of the state tax.
- Late penalty: the greater of $50 or 10% of the amount due on Line 10, even if there is no tax due.
Source: the Florida Department of Revenue, Form DR-15 and Form DR-15N instructions. Last verified September 29, 2026.
Who Must File Form DR-15?
Any business registered with the Department as a sales and use tax dealer must file a return for each reporting period assigned to it, even if no tax is due. If you have no tax due and no deductions or credits, you can file by telephone (telefile) at 800-550-6713.
Some businesses cannot use the simpler DR-15EZ and must use DR-15, including those that paid $200,000 or more in sales and use tax in the prior state fiscal year, sell or deliver into counties with a different surtax rate, rent transient accommodations, sell vehicles, boats or aircraft, operate amusement or vending machines, deal in dyed diesel, or claim certain job or scholarship credits.
If you close or sell the business, file a final return and pay all tax within 15 days after closing or selling.
Common trap: filing only in months with sales. Florida requires a return every period, and a late return carries at least a $50 penalty even when nothing is owed.
How to File Form DR-15
- File and pay online through the Department’s website. It is the only way to earn the collection allowance.
- Or use the paper DR-15 and mail it with a check or money order payable to the Florida Department of Revenue, with your certificate number written on it.
- Complete the back of the return (Lines 15 to 21) first if you have surtax, electricity or diesel items, amusement machine receipts or credits.
- To amend, use an online amended return or write “Amended replacement” on a blank return, filled out as it should have been originally.
- Keep records for at least three years from the filing or due date, whichever is later.
When Is Form DR-15 Due?
Returns and payments are due on the 1st and considered late after the 20th of the month following each reporting period. To avoid penalty and interest on an electronic payment, you must initiate it and receive a confirmation number by 5 p.m. ET on the business day before the 20th. The Department’s Calendar of Electronic Payment Deadlines (Form DR-659) lists them. Estimated tax filers make an additional payment every month starting with the December return.
Where to Mail Form DR-15
If you file on paper, mail the return and payment to: Florida Department of Revenue, 5050 W Tennessee St, Tallahassee, FL 32399-0120. Place the return in the window-style envelope so the address shows, if you received one.
How to Complete Form DR-15 Line by Line
Top of the Return — Certificate Number and Period
The return is preprinted with your certificate number, reporting period, due date and your county’s surtax rate. Do not change the preprinted information; update your account online instead. Use the return for the correct period.
Lines A–E — Gross Sales, Exempt Sales, Taxable Amount and Tax Due
For each line, Column 1 is gross sales (without tax), Column 2 is exempt sales, Column 3 is the taxable amount (Column 1 minus Column 2), and Column 4 is the tax due including discretionary sales surtax. Line A covers sales, leases and licenses of goods, services subject to tax, electricity at 6.95% (2.6% under Chapter 203 and 4.35% under Chapter 212) plus surtax, and dyed diesel. Line B is use tax on purchases not taxed by the seller and not for resale (Columns 1 and 2 are not applicable). Line C is commercial rentals, and sales tax on commercial rentals was repealed effective October 1, 2025. Line D covers transient rentals of rooms and short-term accommodations, and Line E is food and beverage vending computed with the county divisor.
Lines 5–10 — Total Tax, Deductions, Credits and Estimated Tax
| Line | What to enter |
|---|---|
| Line 5 | Adds Column 4 of Lines A to E (less Line C(a)). |
| Line 6 | Lawful deductions, such as tax refunded to customers, but they cannot exceed Line 5. |
| Line 7 | Net tax due. |
| Line 8 | Subtracts estimated tax paid last month and Department credit memos. |
| Line 9 | Adds estimated tax due for the current month for dealers who must prepay. |
| Line 10 | The amount due and cannot be negative. |
Lines 11–14 — Collection Allowance, Penalty, Interest and Amount Due
| Line | What to enter |
|---|---|
| Line 11 | The collection allowance, for on-time electronic filers only: 2.5% of the first $1,200 of Line 10, no more than $30. You may donate it to the Educational Enhancement Trust Fund by checking the box and leaving Line 11 blank. |
| Line 12 | The penalty for a late return or payment: the greater of $50 or 10% of Line 10. |
| Line 13 | Interest, at a floating rate updated each January 1 and July 1. |
| Line 14 | The amount due with the return. |
Lines 15–21 — Surtax and Special Items (Back of Return)
15(a) is the amount of a single item over $5,000 (surtax applies only to the first $5,000 of each item, except for transient rentals and services), 15(b) is taxable amounts not subject to surtax, 15(c) is amounts subject to a surtax rate different from your county’s, and 15(d) is the total surtax due.
| Line | What to enter |
|---|---|
| Line 16 | Florida Tax Credit Scholarship Program motor vehicle sales tax credits. |
| Line 17 | Electricity. |
| Line 18 | Dyed diesel. |
| Line 19 | Amusement machines. |
| Line 20 | Rural or urban high crime area job tax credits. |
| Line 21 | Other authorized credits. |
Common Mistakes to Avoid
- Skipping a period with no sales. A return is required for every period.
- Mailing when you must e-file. Businesses paying $5,000 or more in the prior fiscal year must file and pay electronically.
- Using the wrong county surtax rate. Collect surtax for the county where the item is delivered.
- Forgetting use tax. Untaxed internet and out-of-state purchases belong on Line B.
- Paying at the last minute. Electronic payments must be initiated by 5 p.m. ET the business day before the 20th.
- Claiming a collection allowance on a late or paper return. It is only for on-time electronic filing and payment.
- Reporting commercial rentals as taxable after October 1, 2025. That tax was repealed.
Frequently Asked Questions
When is Form DR-15 due? It is due the 1st and late after the 20th of the month following the reporting period.
What is Florida’s sales tax rate? The general state rate is 6%, plus any discretionary sales surtax imposed by the county.
Do I file if I had no sales? Yes. You can telefile at 800-550-6713 if you have no tax due and no deductions or credits.
What is the collection allowance? 2.5% of the first $1,200 of the Amount Due, up to $30, for filing and paying electronically on time.
Can I use DR-15EZ instead? Only if you qualify; see the DR-15EZ guide.
Where do I mail a paper return? Florida Department of Revenue, 5050 W Tennessee St, Tallahassee, FL 32399-0120.
Final Review Before Filing
- Certificate number and period match the return.
- Each Column 3 equals Column 1 minus Column 2.
- Surtax is included in Column 4 and reported on Line 15(d).
- Lawful deductions do not exceed the tax due.
- Estimated tax is included if required.
- The return and payment are filed electronically by 5 p.m. ET the business day before the 20th, or mailed by the 20th.
- Penalty and interest are added if late.
Sources & verification
- Issuing agency: Florida Department of Revenue
- Official documents: Form DR-15 (PDF) · Form DR-15N instructions (PDF)
- Checked against: Form DR-15 (R. 01/25) and the DR-15N instructions (R. 10/25)
- Last verified: September 29, 2026
Spot an error or an out-of-date figure? Tell us and we will check it against the official source.
General information from the official form and its instructions, not advice for your circumstances. See the full disclaimer.
More Florida Tax Forms forms
- Florida Form DR-1 — Florida Business Tax Application
- Florida Form DR-15EZ — Sales and Use Tax Return (Short Form)
- Florida Form DR-5 — Application for a Consumer’s Certificate of Exemption
- Florida Form F-1120 — Corporate Income/Franchise Tax Return 2025-2026
- Florida Form RT-6 — Employer’s Quarterly Report (Reemployment Tax)