

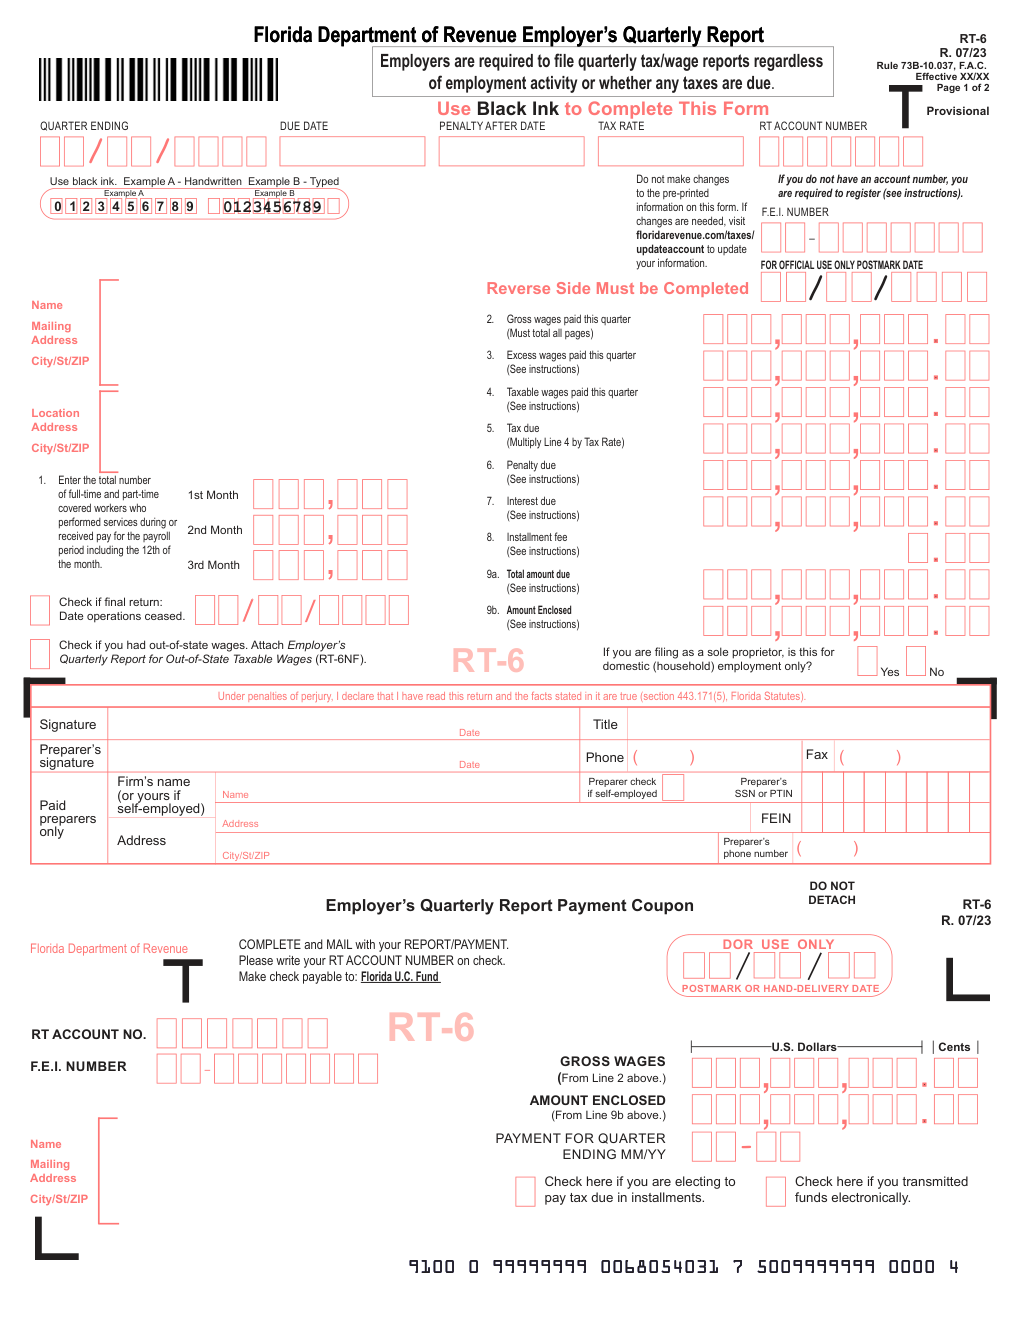
What is Form RT-6?
Quick answer: Form RT-6 is the Employer’s Quarterly Report that Florida employers file to report wages and pay reemployment tax (Florida’s unemployment tax). It is due the last day of the month after each quarter: April 30, July 31, October 31 and January 31. Only the first $7,000 of each employee’s wages in a calendar year is taxable. A report must be filed every quarter even if no wages were paid or no tax is due. Employers with 10 or more employees in any quarter of the prior fiscal year must file and pay electronically.
The RT-6 has two jobs: the front computes the tax on the taxable wages using the tax rate printed on your report, and the back lists every employee with their Social Security number and wages. Errors in Social Security numbers can cost you credit for wages already reported.
You must first be registered. Businesses that don’t have a reemployment tax account number register online, which also happens through the Florida Business Tax Application.
Key Figures — Form RT-6 (R. 07/23)
- Due dates: April 30, July 31, October 31 and January 31; the next business day if the last day falls on a weekend or holiday.
- Taxable wage base: the first $7,000 paid to each employee per calendar year; wages above that are excess wages (Line 3).
- Late penalty: $25 for each 30 days or fraction the report is late, plus interest on unpaid tax.
- E-file requirement: employers with 10 or more employees in any quarter of the prior fiscal year (July 1 to June 30).
- Installments: a $5 fee applies with the first installment if you file and pay on time and choose installments.
- E-Verify certification: employers with 25 or more employees certify use of E-Verify on the first report each calendar year.
Source: the Florida Department of Revenue, Form RT-6 and Form RT-6N instructions. Last verified September 29, 2026.
Who Must File Form RT-6?
Every employer liable under the Florida reemployment assistance program law files an RT-6 for each calendar quarter. This includes a registered employer that had no employees or paid no wages during the quarter, who must still complete, sign and return the report. If wages were paid but no tax is due, the report must still be filed on time.
The report covers only employment during a single calendar quarter. If you do not yet have a reemployment tax account number, register before filing.
Common trap: skipping the report in a quarter with no payroll. A registered employer must still complete, sign and return the RT-6.
How to File Form RT-6
- File and pay online using the Department’s free website. If you are required to e-file, don’t also mail a paper report.
- Or complete the paper RT-6. Use black ink and do not change the preprinted information.
- Enter each employee on the back with their 9-digit Social Security number, name, gross wages and taxable wages, and total each page.
- Transfer the totals to the front, compute the tax and sign the report.
- Correct prior quarters online or use Form RT-8A; do not correct them on your current report.
When Is Form RT-6 Due?
| Quarter | Due (penalty after) |
|---|---|
| January – March | April 30 |
| April – June | July 31 |
| July – September | October 31 |
| October – December | January 31 |
To pay electronically on time, initiate the payment and receive a confirmation number by 5 p.m. ET on the business day before the due date. Reports are considered timely by their electronic date stamp on or before the “Penalty After Date.”
Where to Mail Form RT-6
Employers required to file electronically should not mail a paper report. If you file on paper, mail the RT-6 with payment to the address printed on the form and payment coupon.
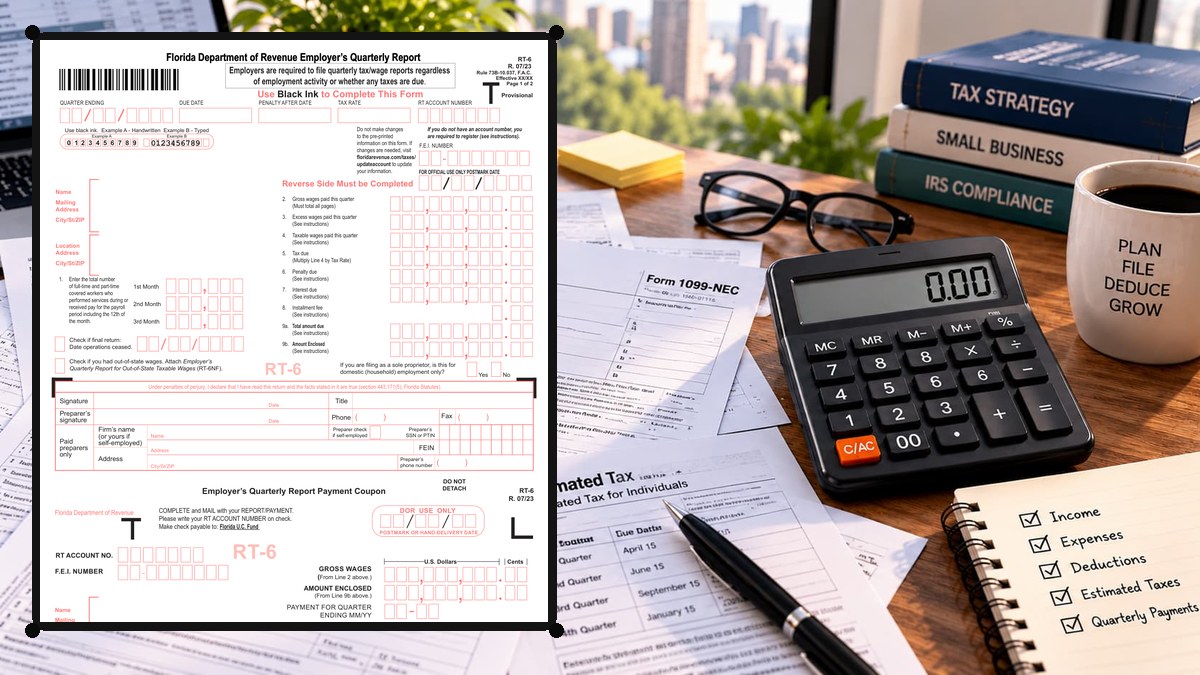
How to Complete Form RT-6 Line by Line
Top of the Report — Quarter, Due Date and Account Number
The report is preprinted with the quarter ending, due date, penalty-after date, tax rate and RT account number. Don’t change preprinted information; update your account online. The FEIN and business address should match your registration.
Lines 1–4 — Employees and Wages
| Line | What to enter |
|---|---|
| Line 1 | The number of full-time and part-time covered employees who worked or received pay for the payroll period including the 12th of each month (first, second and third months). |
| Line 2 | Total gross wages paid before deductions, including salaries, commissions, bonuses, vacation and sick pay, back pay and the cash value of non-cash pay; tips count as wages in the situations the instructions describe. |
| Line 3 | Excess wages, meaning wages over $7,000 to each employee in the calendar year (including wages reported to another state and predecessor wages). |
| Line 4 | Taxable wages: Line 2 minus Line 3. |
Lines 5–9 — Tax, Penalty, Interest and Amount Enclosed
| Line | What to enter |
|---|---|
| Line 5 | Tax due: Line 4 multiplied by your tax rate. |
| Line 6 | The penalty if the report is late: $25 for each 30 days or fraction. |
| Line 7 | Interest on tax not paid by the end of the month after the quarter. |
| Line 8 | The $5 installment fee if you choose installments. |
| Line 9a | The total due (Lines 5 through 8; no payment is needed if under $1). |
| Line 9b | The amount enclosed. |
Installment payments are available for the current quarter: one-quarter of the tax due for quarters ending March 31, one-third for June 30 and one-half for September 30, with the schedule printed in the instructions. Installments for other quarters use Form RT-6INST.
Lines 10–13 — Employee Detail (Back of the Report)
| Line | What to enter |
|---|---|
| Line 10 | Each employee’s nine-digit Social Security number, with leading zeros. If the SSN is missing or invalid, no credit is given for previously reported taxable wages and the first $7,000 on this report is taxed at your rate. |
| Line 11 | The employee’s name. |
| Line 12a | Gross wages this quarter. |
| Line 12b | Taxable wages. |
| Line 13a | Totals gross wages. |
| Line 13b | Totals taxable wages for the page, carried to Lines 2 and 4 on the front. |
Certification, Signature and E-Verify
The report must be signed by the individual owner, corporate president, treasurer or other principal officer, a partner or managing member, or an authorized agent. Complete the paid preparer section if a preparer helped. Employers with 25 or more employees, and public agencies, certify on the first report each calendar year that they use the E-Verify system.
Common Mistakes to Avoid
- Not filing when no wages were paid. A report is still required.
- Wrong or missing Social Security numbers. You lose credit for previously reported wages and can be penalized for an incomplete report.
- Taxing wages above $7,000. Only the first $7,000 per employee per calendar year is taxable.
- Correcting prior quarters on the current report. Use the online correction or RT-8A.
- Mailing a paper report when e-filing is required. Employers with 10 or more employees must file electronically.
- Paying electronically too late. Initiate by 5 p.m. ET the business day before the due date.
- Skipping the E-Verify certification when it applies.
Frequently Asked Questions
When is the RT-6 due? By the last day of the month after each quarter: April 30, July 31, October 31 and January 31.
What wages are taxable? The first $7,000 paid to each employee in a calendar year.
Do I file if I had no employees? Yes. A registered employer must file every quarter.
What is the late penalty? $25 for each 30 days or fraction of a month the report is late, plus interest.
Can I pay in installments? Yes, for the amounts described in the instructions, with a $5 fee with the first installment.
How do I correct a report? Online through the File and Pay website or with Form RT-8A if you are not required to file electronically.
Final Review Before Filing
- The report covers only one calendar quarter.
- Every employee’s SSN is complete with leading zeros.
- Excess wages over $7,000 are on Line 3.
- Taxable wages on Line 4 equal the total of Line 13b.
- Tax is Line 4 times your rate.
- Penalty and interest are added if late.
- The report is signed and filed by the due date, electronically if required.
Sources & verification
- Issuing agency: Florida Department of Revenue
- Official documents: Form RT-6 (PDF) · Form RT-6N instructions (PDF)
- Checked against: Form RT-6 and the RT-6N instructions (R. 07/23)
- Last verified: September 29, 2026
Spot an error or an out-of-date figure? Tell us and we will check it against the official source.
General information from the official form and its instructions, not advice for your circumstances. See the full disclaimer.