

What is Form 05-102?
Quick answer: Form 05-102 is the Public Information Report (PIR). Every corporation, LLC, limited partnership, professional association and financial institution with a Texas franchise tax responsibility must file one, even if no franchise tax is owed. It lists officers, directors, managers, and members or general partners, plus ownership relationships and the registered agent. It is due on the same date as the franchise tax report, May 15, 2026, and must be signed. Failing to file can put an entity’s right to transact business in Texas at risk.
Unlike the franchise tax report, which is about money, the PIR is about who is behind the entity. The information is available to the public and, for entities registered with the Secretary of State, it is passed on to that office.
Many small businesses never owe franchise tax because their revenue is under the no tax due threshold, and assume they have nothing to file. The PIR (or the related Ownership Information Report) is the filing that fills that gap.
Key Figures — Report Year 2026 (Form 05-102)
- Who: each corporation, LLC, limited partnership, professional association and financial institution with a franchise tax responsibility. A separate PIR is needed for each entity that files its own report or is part of a combined group.
- Due date: the same as the franchise tax report, May 15, 2026.
- Signature: an officer, director or other authorized person, which can include an authorized paid preparer.
- Risk: filing the tax report and paying the tax does not protect an entity that fails to file a completed, signed PIR; the right to transact business can be forfeited.
- Not required for: passive entities and new veteran-owned businesses during their initial five-year period.
- Ownership Information Report (Form 05-167) is used instead by professional associations and financial institutions in the cases the instructions describe.
Source: the Texas Comptroller of Public Accounts, 2026 Form 05-102 and Form 05-915 instructions. Last verified September 29, 2026.
Who Must File Form 05-102?
You must file the PIR if the entity is a corporation, limited liability company, limited partnership, professional association or financial institution that has a franchise tax responsibility, including entities that owe no tax because they are at or below the no tax due threshold. A separate PIR is required for each such entity that files a separate franchise tax report or is part of a combined group, unless the entity is not organized in Texas and has no Texas nexus.
You generally do not file a PIR if you are a passive entity, or a new veteran-owned business during its initial five-year exemption period. A PIR is also not required with a final report.
Common trap: entities under the revenue threshold assume nothing is due. Without a completed, signed PIR (or OIR), the annual filing requirement is not met, even though no tax is owed.
How to File Form 05-102
- File online through Webfile. The Comptroller notes that entities that need only a PIR or OIR can easily file the report electronically.
- Or mail the signed paper form to the Comptroller.
- If nothing has changed from the information preprinted on the form, blacken the circle for no changes and complete Sections B and C. If nothing is preprinted, complete all applicable items.
- Use additional sheets if you have more officers, directors or owned entities than the form has room for.
- Sign and date the report.
When Is Form 05-102 Due?
The PIR is due on the same date as the franchise tax report: May 15, 2026 for report year 2026. If the date falls on a weekend or holiday it moves to the next business day. An entity at or below the threshold that cannot file by that date may request a zero money extension through Webfile or Form 05-164.
Where to Mail Form 05-102
Texas Comptroller of Public Accounts, P.O. Box 149348, Austin, TX 78714-9348. Change of registered agent or registered office must be filed with the Secretary of State, not on this form.
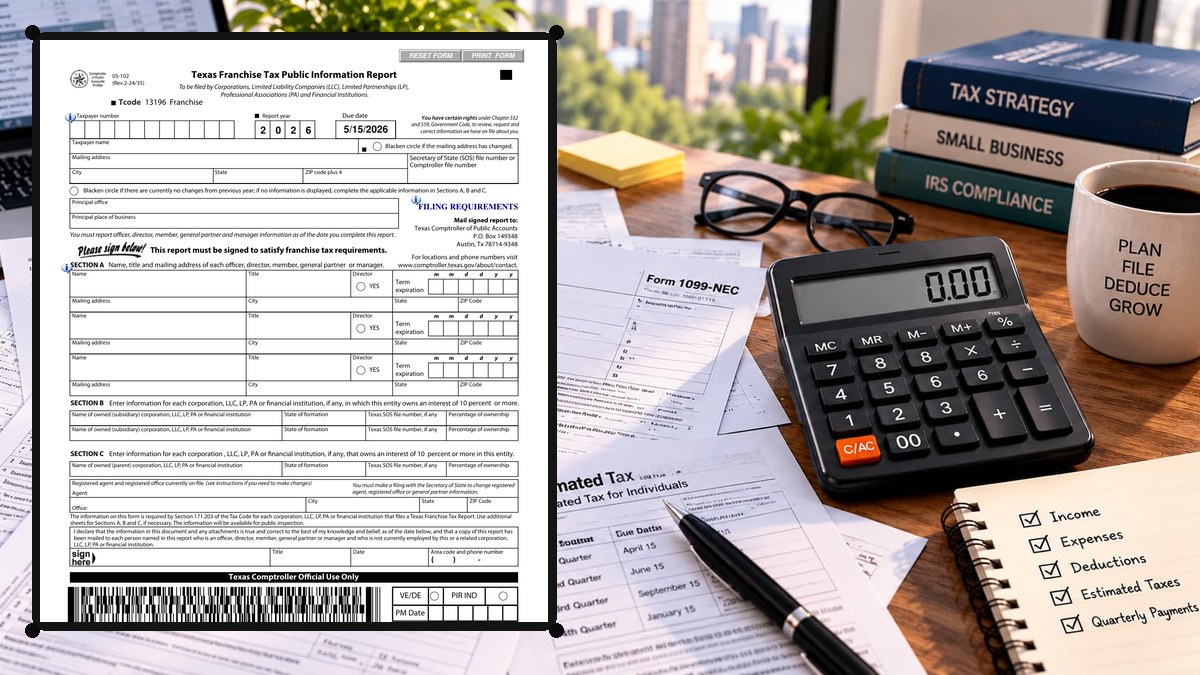
How to Complete Form 05-102 Line by Line
Top of the Form — Taxpayer Information
Confirm the taxpayer number, report year (2026), due date (5/15/2026), name and mailing address; blacken the circle if the mailing address has changed. Enter the principal place of business. If the form shows no changes from last year, blacken the circle and complete Sections B and C; if no information is preprinted, complete Sections A, B and C fully.
Section A — Officers, Directors, Members and Managers
Give the name, title and mailing address of each officer, director, member, general partner and manager as of the filing date. Texas profit corporations and professional corporations list all officers, including the president and secretary, and all directors; one person may hold all offices. Texas nonprofit corporations list all officers, with different persons as president and secretary and at least three directors. Texas LLCs list all managers and, if member-managed, all members. Non-Texas entities list the people their home law requires. Limited partnerships include all general partners, and professional associations report the members of their executive committee. Mark “Director” and the term expiration where the form asks.
Section B — Owned Subsidiaries
List each corporation, LLC, LP, PA or financial institution, if any, in which this entity owns an interest of 10 percent or more: name, state of formation, Texas Secretary of State file number and percentage of ownership.
Section C — Parent Entities and Registered Agent
List each entity that owns 10 percent or more of this entity, with the same details. The form also shows the registered agent and registered office currently on file. You cannot change them here; you must make a filing with the Secretary of State to change the registered agent, registered office or general partner information.
Signature and Certification
The signer declares the information is true and correct and that a copy of the report has been mailed to each person named who is an officer, director, member, general partner or manager and is not currently employed by the entity or a related entity. Add title, date and phone number. The information is required by Section 171.203 of the Tax Code and is available for public inspection.
Common Mistakes to Avoid
- Not filing because no tax is due. The PIR or OIR is still required.
- Leaving out officers or directors. Each required person must be listed as of the date you file.
- Trying to change the registered agent here. That requires a filing with the Secretary of State.
- Skipping the signature. An unsigned report does not satisfy the requirement.
- Forgetting the copy notice. The report certifies that a copy was mailed to certain named persons.
- Filing one PIR for a group. Each entity that files its own report or is in a combined group needs its own.
Frequently Asked Questions
Do I file a PIR if I owe no franchise tax? Yes. Entities under the no tax due threshold still file a PIR or OIR.
What happens if I don’t file? The entity’s right to transact business in Texas can be forfeited, with consequences such as losing the right to sue or defend in Texas courts and personal liability for officers and directors for certain debts.
Where do I change my registered agent? With the Texas Secretary of State.
Can I correct a PIR after filing? An amended PIR can be filed with a cover letter explaining the error; otherwise, report changes on the next PIR.
Is the information public? Yes. It is available for public inspection.
What is the difference between the PIR and the OIR? They serve the same purpose, but the OIR (Form 05-167) applies to certain entity types, such as professional associations and financial institutions.
Final Review Before Filing
- Taxpayer name, number and address are correct.
- All officers, directors, members or managers are listed with titles.
- Sections B and C list owned and owning entities with 10 percent or more.
- Registered agent details are accurate with the Secretary of State.
- The report is signed and dated.
- It is filed with the franchise tax report by the due date.
Sources & verification
- Issuing agency: Texas Comptroller of Public Accounts
- Official documents: Form 05-102 (PDF) · 2026 Texas Franchise Tax Report Information and Instructions (05-915) (PDF)
- Checked against: the 2026 Form 05-102 and the 2026 Form 05-915 instructions booklet
- Last verified: September 29, 2026
Spot an error or an out-of-date figure? Tell us and we will check it against the official source.
General information from the official form and its instructions, not advice for your circumstances. See the full disclaimer.
More Texas Tax Forms forms
- Texas Form 01-114 — Sales and Use Tax Return
- Texas Form 01-339 — Sales and Use Tax Resale Certificate and Exemption Certification
- Texas Form 05-158 — Franchise Tax Report (Long Form) 2025-2026
- Texas Form 05-164 — Franchise Tax Extension Request 2025-2026
- Texas Form 05-169 — Franchise Tax EZ Computation Report 2025-2026